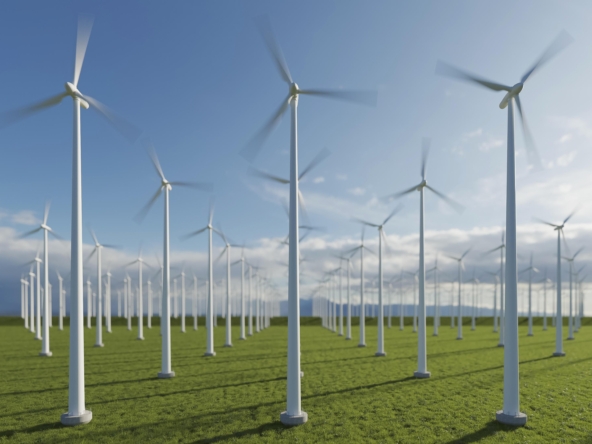
The portfolio benefits from long-term contracted revenues under existing PPAs, providing visibility over near-term cash generation.
Following expiry of the existing PPAs, the assets are estimated to have approximately 13 additional years of economic life, creating an opportunity to capture additional value through re-contracting, bilateral power sales or alternative commercialization strategies.
Further technical, legal, commercial and financial information is available to qualified parties following execution of an NDA.
Hypothetical Financial Model: 30.24 MW Operational Wind Portfolio (Northeast Brazil)
All figures in USD millions unless stated otherwise. Assumed conversion rate: 5.09 BRL/USD.
1. Key Operating & Commercial Baseline Assumptions
| Operating Metric |
Wind Farm 1 |
Wind Farm 2 |
Consolidated Portfolio |
| Installed Capacity |
15.12 MW |
15.12 MW |
30.24 MW |
| Estimated Annual Generation |
48.7 GWh |
47.4 GWh |
96.1 GWh (~96.0 GWh target) |
| Implied Capacity Factor |
~36.8% |
~35.8% |
~36.3% |
| PPA Expiry Date |
December 31, 2031 |
December 31, 2032 |
2031 (WF1) / 2032 (WF2) |
| Contracted Net Cash Flow |
— |
— |
$5.26M / year |
| Merchant / Post-PPA Net Cash Flow |
— |
— |
$4.25M / year |
| Remaining Post-PPA Economic Life |
13 years (to ~2044) |
13 years (to ~2045) |
~13 years |
| Existing Capital Structure |
Zero Debt |
Zero Debt |
100% Equity / Debt-Free |
2. Representative Revenue, O&M & Net Cash Flow Profile (Consolidated P&L Proxy)
Because the portfolio generates an agreed-upon $5.26M/year in contracted net cash flow after operating costs and statutory Brazilian corporate taxes (Lucro Real / Presumido), the operational proxy breaks down as follows:
| Financial Line Item (US$ M) |
Contracted Period (2027–2031) |
Transition Year (2032)* |
Post-PPA Period (2033–2044) |
| Gross Power Revenue |
$7.85 (equiv. ~$81.7/MWh) |
$6.90 |
$6.25 (equiv. ~$65.0/MWh) |
| Scheduled O&M & Turbine Service Agreements |
($1.15) |
($1.15) |
($1.25) (Aging buffer) |
| Land Leases, Royalties & Concession Levies |
($0.25) |
($0.23) |
($0.20) |
| Transmission (TUST) & Grid Connection Tariffs |
($0.35) |
($0.35) |
($0.35) |
| General & Administrative / SPV Management |
($0.20) |
($0.20) |
($0.20) |
| EBITDA |
$5.90 (75.2% margin) |
$4.97 (72.0% margin) |
$4.25 (68.0% margin) |
| Maintenance CapEx Reserve |
($0.15) |
($0.18) |
($0.22) |
| Net Income Tax & Social Contributions (CSLL/PIS/COFINS) |
($0.49) |
($0.42) |
($0.38) |
| Unlevered Free Cash Flow (Net Cash Flow) |
$5.26 |
$4.37 |
$3.65 – $4.25 |
*Note: In 2032, Wind Farm 1 operates under merchant/free-market conditions while Wind Farm 2 completes its final contracted PPA year.
3. Indicative Unlevered Cash Flow Schedule (15-Year Horizon, 2027–2041)
| Year |
Asset Regime |
WF1 Status |
WF2 Status |
Net Cash Flow (US$ M) |
| 2027 |
Fully Contracted |
Regulated PPA |
Regulated PPA |
$5.26 |
| 2028 |
Fully Contracted |
Regulated PPA |
Regulated PPA |
$5.26 |
| 2029 |
Fully Contracted |
Regulated PPA |
Regulated PPA |
$5.26 |
| 2030 |
Fully Contracted |
Regulated PPA |
Regulated PPA |
$5.26 |
| 2031 |
Fully Contracted |
Regulated PPA (Final Yr) |
Regulated PPA |
$5.26 |
| 2032 |
Transition |
Bilateral / Free Market |
Regulated PPA (Final Yr) |
$4.75 |
| 2033 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2034 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2035 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2036 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2037 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2038 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2039 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2040 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| 2041 |
Full Post-PPA Life |
Bilateral / ACL Merchant |
Bilateral / ACL Merchant |
$4.25 |
| Cumulative |
|
|
|
$70.50M |
4. Indicative Unlevered Valuation Matrix (Discounted Cash Flow Sensitivity)
Valuation reflects a DCF of net cash flows across the remaining ~18 years of operational life (5 contracted years + 13 post-PPA years):
| Unlevered Cost of Capital (Discount Rate) |
Implied Enterprise Value (US$ M) |
Implied Multiple on Contracted Cash Flow |
Implied EV / Installed MW |
| 7.5% (Low Risk / BRL Hedged) |
$44.6M |
8.48x |
$1.47M / MW |
| 8.5% (Core Infrastructure Hurdle) |
$41.1M |
7.81x |
$1.36M / MW |
| 9.5% (Emerging Market Benchmark) |
$38.1M |
7.24x |
$1.26M / MW |
| 10.5% (Conservative Equity Return) |
$35.4M |
6.73x |
$1.17M / MW |
This hypothetical financial model and accompanying presentation (the “Document”) are provided solely for preliminary illustrative, structural, and evaluation purposes. This Document does not constitute, nor shall it be deemed to constitute, an offer to sell, a solicitation of an offer to buy, an underwriting commitment, or an investment recommendation regarding the shares, quotas, operating concessions, physical assets, or special purpose vehicles (SPVs) of the 30.24 MW wind portfolio or any affiliated entities.
Hypothetical Projections & Forward-Looking Risks
All financial figures, capacity factors, production levels (96.0 GWh/yr), generation estimates, operating cost assumptions, merchant energy pricing forecasts, tax regimes, and post-PPA yields (~US$4.25M/yr) are forward-looking and based on indicative assumptions. These statements involve substantial known and unknown risks, uncertainties, and contingencies, including but not limited to:
-
Wind resource variability (P50/P90 generation deviations) and climate patterns in Northeast Brazil;
-
Grid curtailment, transmission constraints, and system operator dispatch orders (ONS);
-
Fluctuations in the Brazilian Free Energy Market (Ambiente de Contratação Livre — ACL) and Settlement Price for Differences (PLD);
-
Foreign exchange volatility between the Brazilian Real (BRL) and the United States Dollar (USD);
-
Inflationary adjustments, escalation of operations and maintenance (O&M) contracts, and replacement part supply chains;
-
Regulatory, statutory, concession, and fiscal changes by ANEEL, CCEE, or Brazilian federal/state revenue authorities.
Actual cash flows and terminal asset values may differ materially from those modeled herein.
No Representations, Warranties, or Reliance
No representation, warranty, or undertaking—express or implied—is made by the asset owners, operators, financial modelers, advisors, or their respective directors, officers, or agents regarding the accuracy, completeness, authenticity, or reasonableness of the data, technical parameters, or projections set forth in this Document. Recipient expressly agrees that no commercial reliance may be placed on this Document.
Absolute Exclusion of Liability
To the fullest extent permitted by applicable law, the authors, asset owners, advisors, affiliates, and representatives expressly disclaim all liability (whether in contract, tort, strict liability, negligence, or otherwise) for any direct, indirect, incidental, consequential, special, punitive, or reliance damages, including lost profits, loss of business opportunity, or transaction expenses incurred by the recipient or any third party arising out of or in connection with the use of, or reliance upon, any information, calculations, assumptions, or omissions contained in this Document.
Requirement for Independent Due Diligence
Receipt of this Document does not substitute for a rigorous, independent investigation. Qualified prospective purchasers must conduct their own independent legal, tax, hydrogeological, wind resource (anemometric review), technical (turbine condition assessment), regulatory, and accounting due diligence with authorized external counsel and technical advisors prior to entering into any transaction or executing binding documentation. All technical, operational, and commercial data rooms will remain subject to the terms of an executed Non-Disclosure Agreement (NDA).