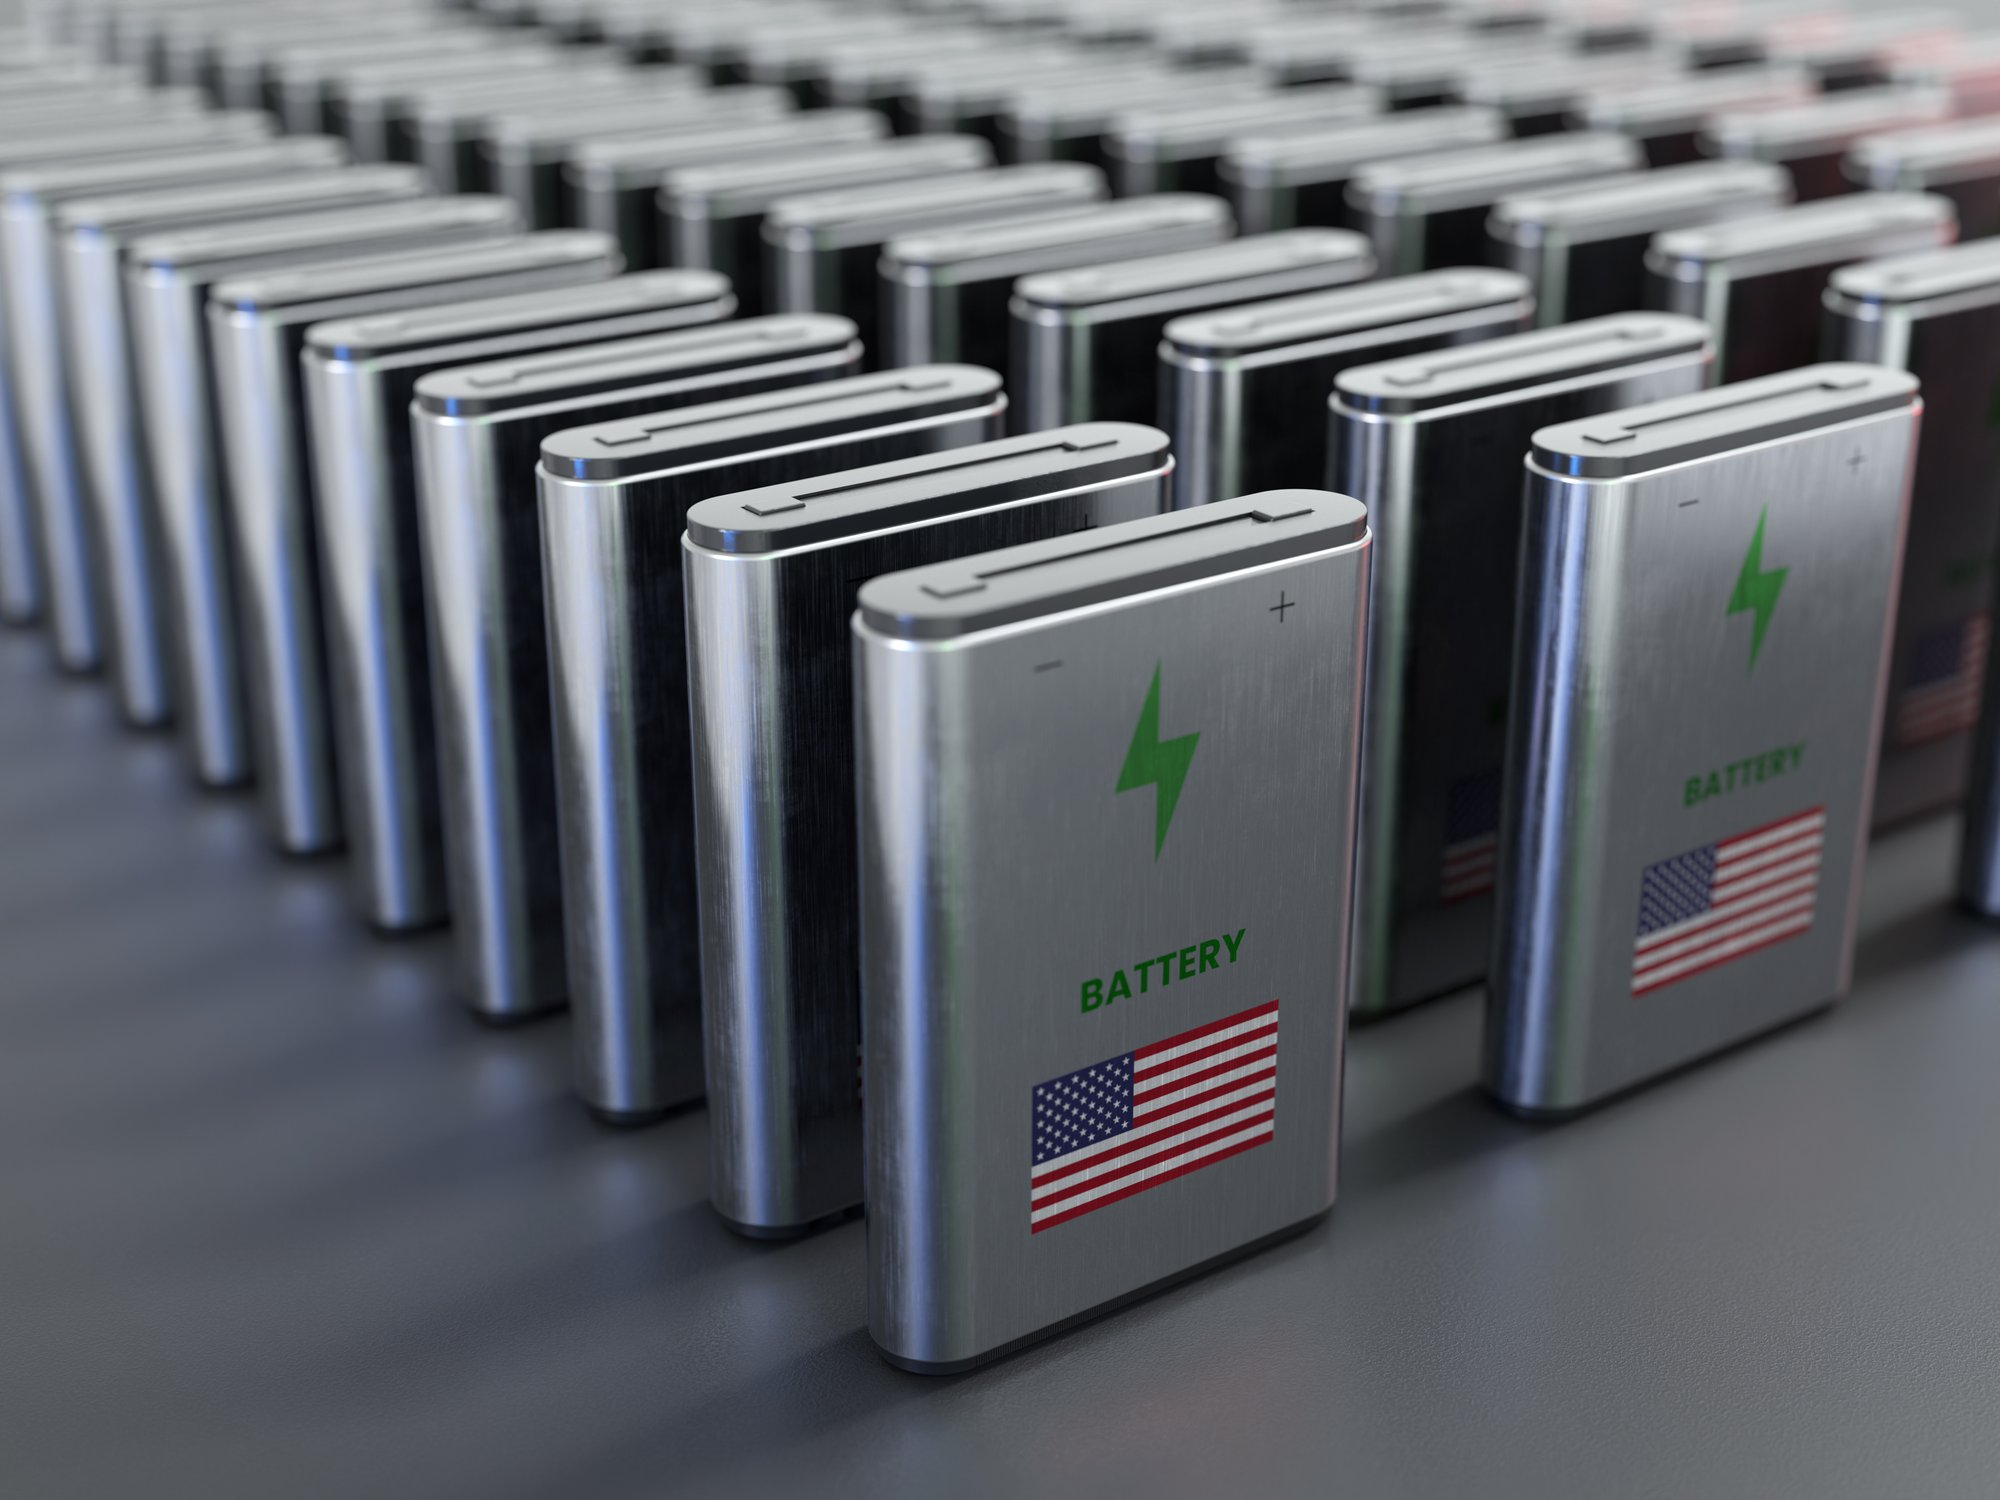
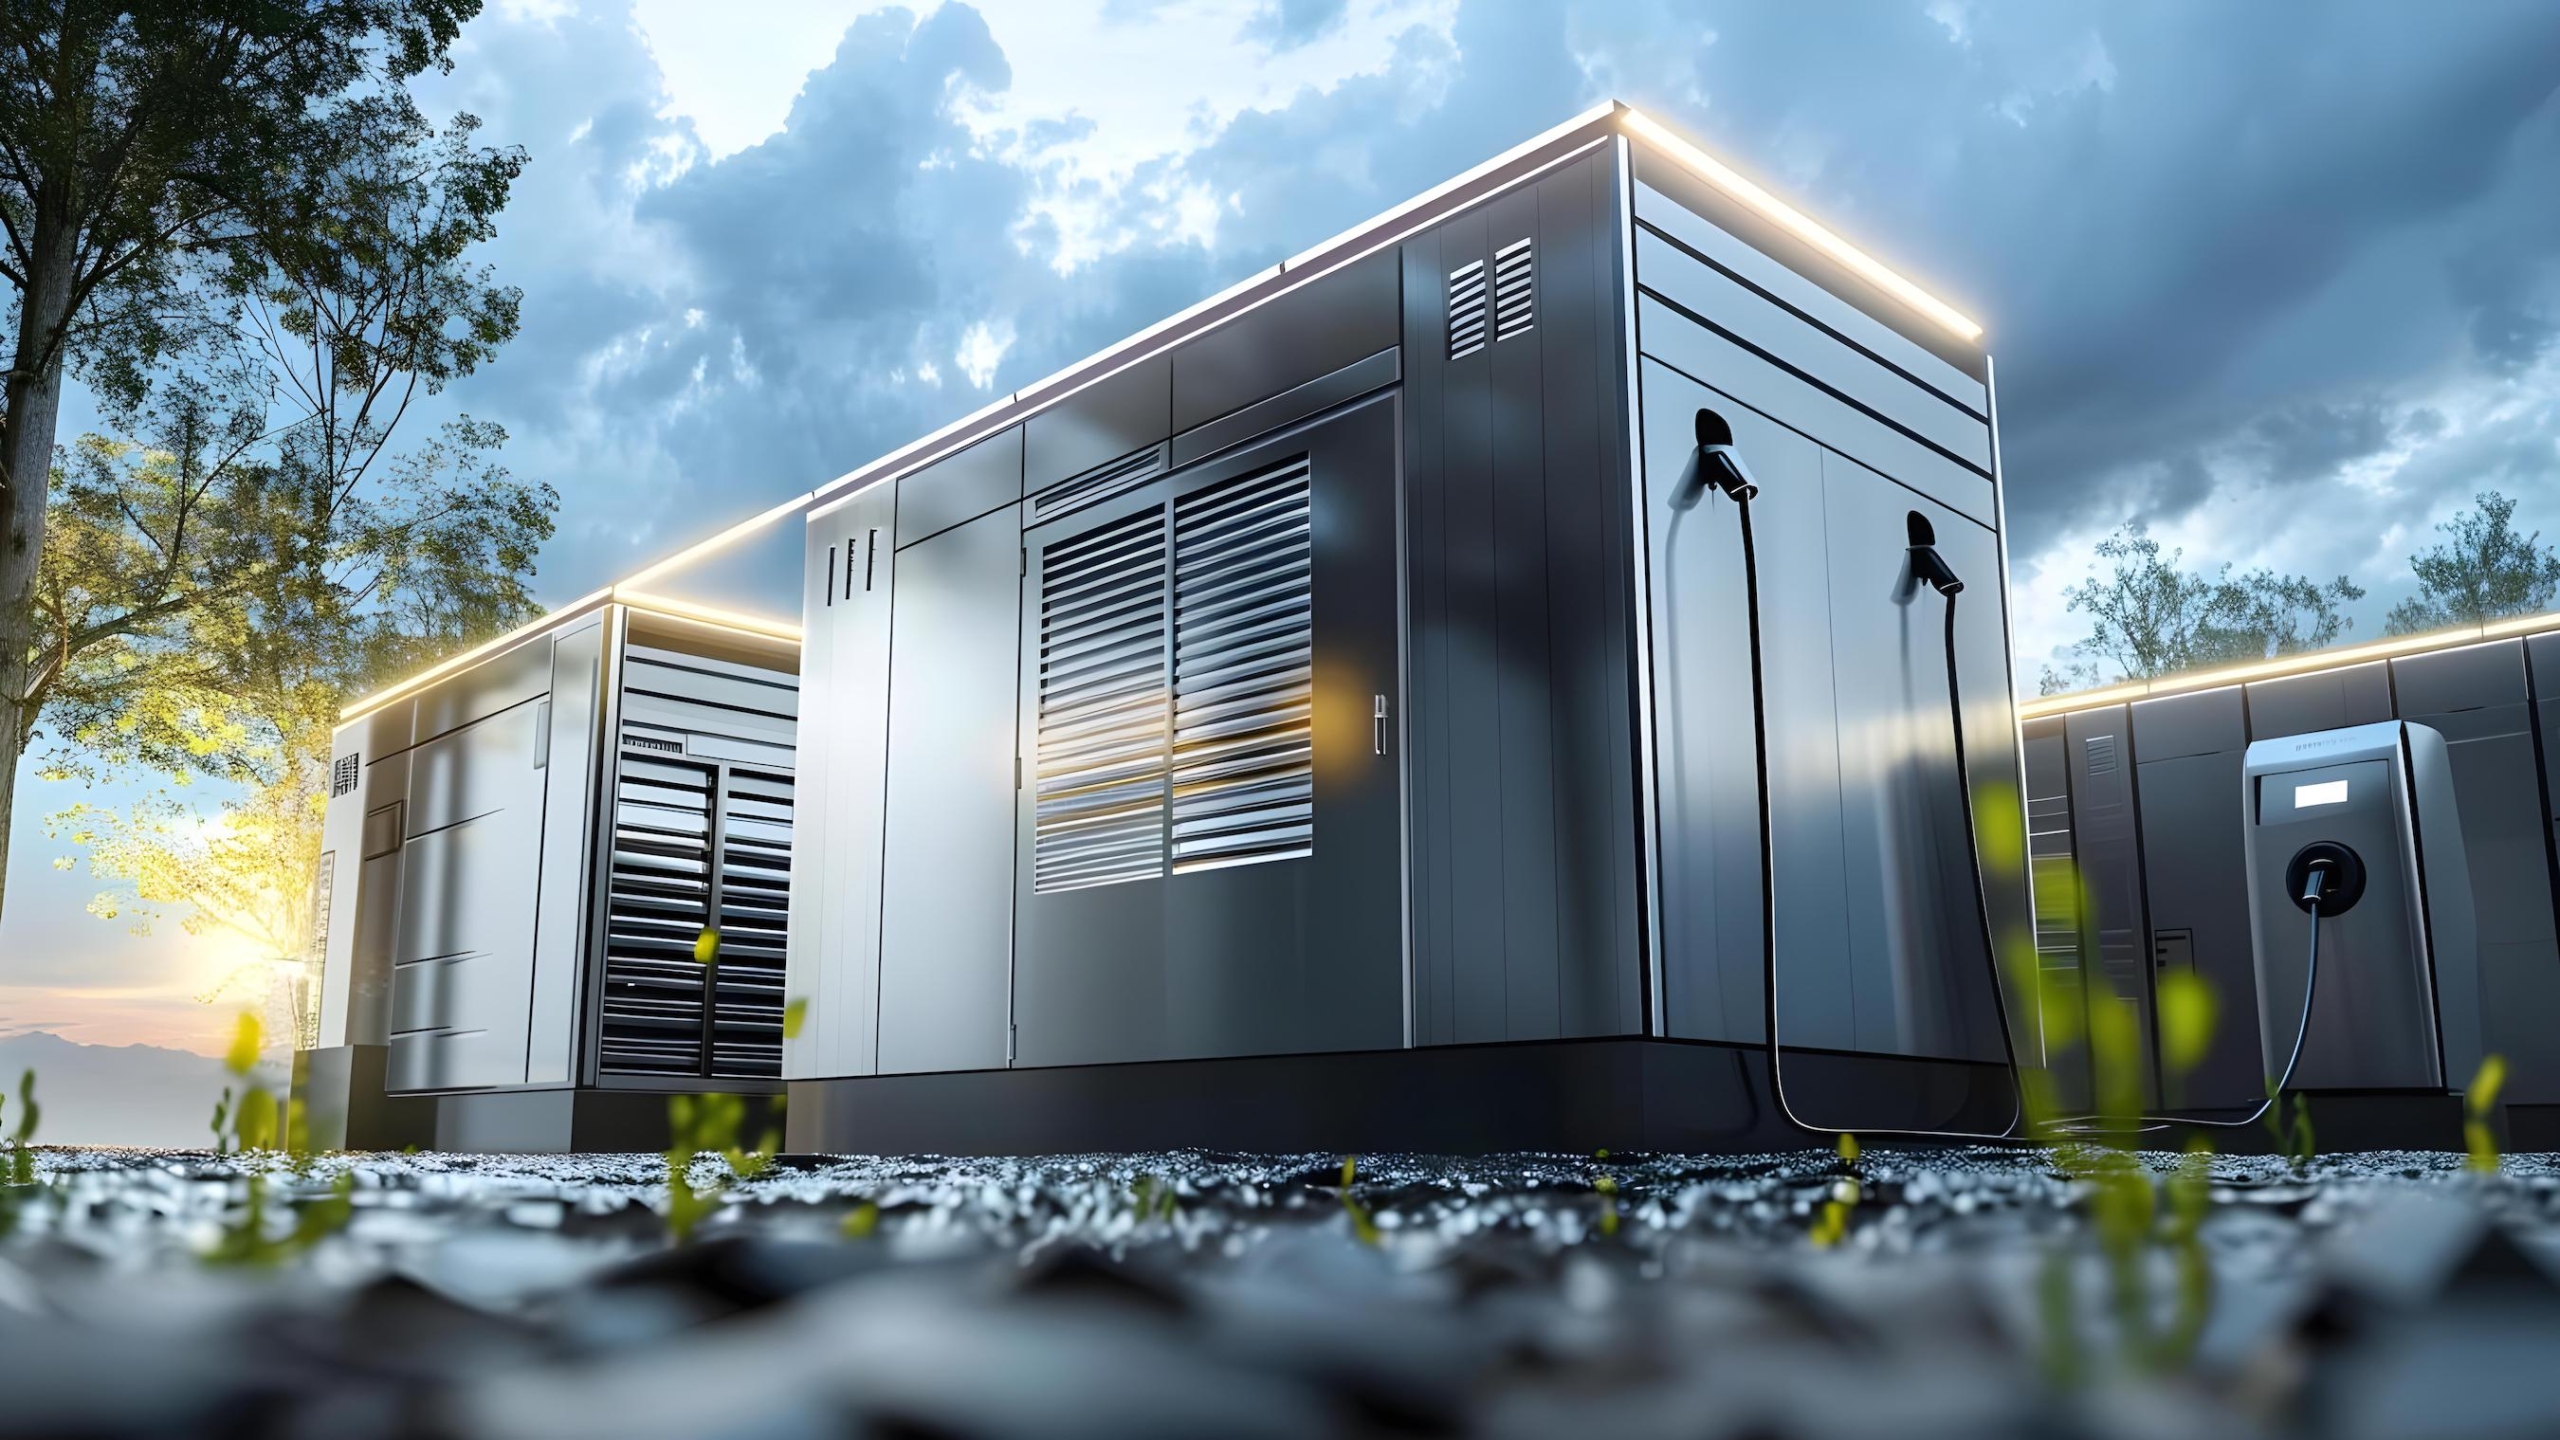
This is a 205 MW / 551.65 MWh DC utility-scale battery energy storage project located in Midland County, Texas, featuring a 2.7-hour discharge duration on DC nameplate. The system utilizes 110 Tier-1 U.S.-manufactured LFP battery containers (5.015 MWh each, produced in the Midwest) paired with utility-grade medium-voltage conversion stations, constructed under the supervision of a leading national balance-of-plant EPC contractor by discipline and specialized civil works partners. Capacity retention adheres strictly to the original equipment manufacturer’s technical-proposal degradation curve, reaching 66.6% of initial nameplate capacity in Year 20 with no mid-life augmentation.
The sponsor team’s experience spans C&I, distributed generation and utility-scale renewable projects, including EPC and project execution, development, commercialisation and asset management across US energy markets.
Total CapEx is $154.6 million, or $280 per kWh of DC nameplate, with the $12.8 million Oncor network upgrade carried outside CapEx as a separate project cost. Total uses at commercial operation are $197.9 million, funded by $63.3 million of senior term debt, a $49.4 million ITC bridge and $85.2 million of equity – a 42.6% / 57.4% debt-to-equity split of permanent capital. Senior debt is sized on the contracted Nephila floor case at a 1.20x minimum debt-service coverage ratio. During construction, equity funds the milestone draws in full for the first seven months before the senior facility is drawn. The 40% investment tax credit ($61.8 million gross) is monetised through a Section 6418 transfer at $0.92 per dollar of credit; the bridge is repaid from the $54.9 million of net proceeds 9 months after commercial operation, with the $8.4 million Nephila ECOD instalment paid from the bridge.
The three independent market cases show the following. In the P50 base case the project earns $503.4 million of revenue over 20 years, a 19.1% levered after-tax project IRR, a 23.5% investor IRR and a 2.08x multiple, with after-tax payback in year 6. In the P90 downside case revenue falls to $344.9 million; senior debt is unchanged because it is sized on the contracted floor, and the investor IRR is 7.7% with a 1.32x multiple and payback in year 9. In the P20 upside case revenue reaches $801.7 million and the levered after-tax project IRR is 38.3%.
Distributions follow a 10% cumulative compounded preference, then a full return of the investor’s $85.2 million, then 70% to the investor and 30% to Bear Creek Energy Partners until the investor has received 2.0x its capital ($170.4 million), after which residual cash is split 49% to the investor and 51% to Bear Creek. The senior debt is supported by a 7-year contracted Nephila revenue floor of $56,170 per MW-year, and all 17 internal model checks and the five investor checks tie to zero.
All financial information, performance metrics, projections, estimates, historical statements, multiples, and business valuations (collectively, the “Financial Information”) presented, distributed, published, or otherwise communicated by MergersCorp M&A International, MergersUS Inc., its parent companies, subsidiaries, affiliate offices, member firms, officers, directors, partners, employees, agents, and independent contractors (collectively, “MergersCorp”) are provided solely for general informational and reference purposes.
All information is provided on an “AS IS” and “AS AVAILABLE” basis without warranties, representations, or covenants of any kind, whether express, implied, statutory, or otherwise, including, without limitation, any warranties of accuracy, completeness, timeliness, merchantability, fitness for a particular purpose, or non-infringement.
2. Third-Party and Client-Supplied Data
The Financial Information contained in any teaser, confidential information memorandum (CIM), website listing, pitch deck, or correspondence is derived primarily or entirely from unverified data supplied by sellers, prospective buyers, target companies, or other third-party sources. MergersCorp has not independently audited, verified, authenticated, or evaluated any such figures or source records. MergersCorp does not endorse, substantiate, or guarantee the correctness, authenticity, or reliability of any revenue figures, earnings before interest, taxes, depreciation, and amortization (EBITDA), cash flow analyses, balance sheets, inventory valuations, asset listings, customer concentrations, or tax computations.
3. Forward-Looking Statements and Projections
Materials provided may contain forward-looking statements, financial models, expected synergies, future market forecasts, pro-forma financials, and projected business growth. These statements are merely prospective estimates subject to significant market risks, competitive pressures, macro-economic fluctuations, and unforeseen contingencies. Actual results will inevitably vary from projections, and variations may be material and adverse. MergersCorp explicitly disclaims any representation that any past performance will recur or that future targets will be met or maintained.
4. No Advisory, Legal, Accounting, or Fiduciary Duty
MergersCorp does not provide legal, tax, certified public accounting, formal audit, or fiduciary advisory services. Receipt or review of any Financial Information does not establish an investment advisory or fiduciary relationship between the recipient and MergersCorp. Prospective purchasers, investors, and parties to any transaction must not rely on the Financial Information provided and are strongly urged to engage qualified, independent legal counsel, certified public accountants (CPAs), and financial consultants to conduct their own independent audit and due diligence.
5. Independent Member Firm Structure
MergersCorp M&A International operates as a network of independent affiliate offices and member firms. No partner, affiliate office, or member firm has the authority to bind or assume legal liability on behalf of MergersUS Inc. or any other member firm. Each firm renders services strictly on its own account and risk.
6. Comprehensive Limitation of Liability
To the fullest extent permitted by applicable law, in no event shall MergersCorp, its affiliates, members, managers, officers, or representatives be liable to any party for any direct, indirect, incidental, consequential, special, punitive, exemplary, or statutory damages whatsoever—including, without limitation:
-
Loss of profits, revenue, or business opportunities;
-
Purchase price discrepancies, valuation overstatements, or impairment of goodwill;
-
Business interruptions, operational downtime, or transaction termination costs;
-
Inaccurate seller/buyer figures, bookkeeping errors, or omissions of material facts;
arising out of, in connection with, or resulting from the use of, reliance upon, or inability to use any Financial Information or business listing materials provided by or accessed through MergersCorp, whether founded in contract, tort (including negligence), strict liability, misrepresentation, or otherwise, even if advised of the possibility of such damages.
7. Acknowledgment and Sole Remedy
By accessing, reviewing, or receiving any Financial Information from MergersCorp, you expressly acknowledge and agree that you are solely responsible for conducting your own independent due diligence, verification, and inspection before executing any binding agreements, letters of intent, or financial commitments. If you are dissatisfied with any Financial Information, your sole and exclusive remedy is to discontinue reviewing the materials and refrain from entering into the transaction.
(Note: While this text covers standard institutional M&A disclaimers and mirrors MergersCorp’s terms of service, jurisdictional rules on liability waivers—especially regarding gross negligence or fraudulent misrepresentation—can vary. Have a corporate attorney review this within the context of your specific Non-Disclosure Agreement (NDA), CIM, or Engagement Agreement.)