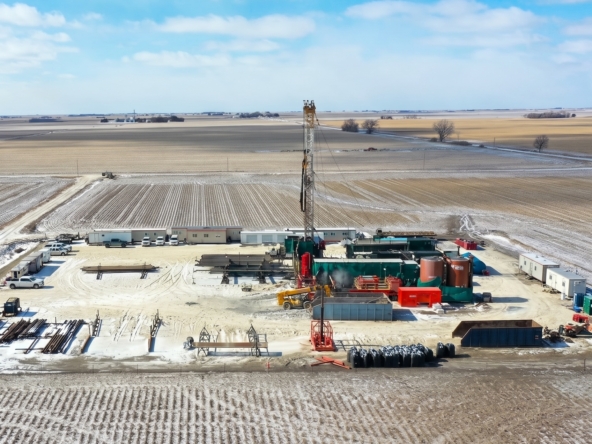
This project is an institutional pre-drill exploration program focused on delineating subsurface natural (geological) hydrogen and co-occurring strategic helium systems in the U.S. Gulf Coast basin (Texas). The sponsor is raising $13.5M in staged, milestone-gated capital over an 18 to 19 month exploration lifecycle to convert existing proprietary desktop reconnaissance into 1 to 2 substantiated, drill-ready subsurface targets. This structure isolates pre-drill geologic confirmation from downstream development risk, minimizing dry-hole exposure prior to full-scale drilling and plant capital deployment.
Core Investment Thesis & Strategic Moat
-
Empirical Field Provenance: The venture’s proprietary predictive geological targeting is backed by direct historical operating leadership on the first benchmark U.S. natural hydrogen exploration well (drilled in Fillmore County, Nebraska in 2019), which logged high-grade wellhead gas tests of 44% hydrogen and 12.8% helium.
-
Disruptive Cost & Carbon Profile: Natural geologic extraction yields an estimated production cost of $0.50 to $1.00 per kg of hydrogen with an ultra-low carbon intensity (~0.4 kg CO2e per kg of hydrogen), heavily outcompeting both green water-electrolysis ($4.50 to $12.00 per kg) and fossil grey SMR ($1.00 to $3.00 per kg) routes.
-
High-Margin Helium Kicker: Helium demand in advanced semiconductor manufacturing, quantum computing, cryogenics, and aerospace creates an outsized revenue cushion. Modeled conservatively at an initial 2% concentration by volume and priced at a discount to spot, helium serves as a primary driver of project capital efficiency and early payback.
-
Texas Jurisdiction & Infrastructure Advantage: Texas provides clear administrative and mineral rights pathways (~1 month / ~$200K acquisition profile), competitive rig mobilization rates, and direct access to heavy industrial offtake clusters (refineries, ammonia, methanol, and chemical complexes) along Gulf Coast distribution corridors.
Capital Tranches & Milestone De-Risking Gates
Pre-drill equity deployment is governed by technical decision gates, releasing capital only upon definitive geologic evidence:
Project Financial Model (Per Single Commercial Structure)
The financial model below details an illustrative commercial exploitation scenario for one target structure under baseline Texas execution conditions against an upside regional benchmark, incorporating full extraction, separation, and purification surface infrastructure.
1. Baseline Assumptions & Technical Specifications
2. Steady-State Annual Operating Performance (Year 5+)
Reflecting 97% operational availability across both product streams:
3. Indicative Multi-Year Project Cash Flow Model (10-Year Snapshot in $M)
Reflecting a 4-year development and construction period followed by steady-state production:
| Line Item ($M) |
Year 1 |
Year 2 |
Year 3 |
Year 4 |
Year 5 (COD) |
Year 6 |
Year 7 |
Year 8 |
Year 9 |
Year 10 |
| Pre-Drill Equity Tranche |
($4.50) |
($9.00) |
— |
— |
— |
— |
— |
— |
— |
— |
| Facility Construction CAPEX |
— |
— |
($75.00) |
($75.00) |
— |
— |
— |
— |
— |
— |
| Commercial Revenue (TX Base) |
— |
— |
— |
— |
$160.05 |
$160.05 |
$160.05 |
$160.05 |
$160.05 |
$160.05 |
| Operating Costs (TX Base) |
— |
— |
— |
— |
($32.01) |
($32.01) |
($32.01) |
($32.01) |
($32.01) |
($32.01) |
| Net Operating Cash Flow |
($4.50) |
($9.00) |
($75.00) |
($75.00) |
$128.04 |
$128.04 |
$128.04 |
$128.04 |
$128.04 |
$128.04 |
| Cumulative Net Cash Flow |
($4.50) |
($13.50) |
($88.50) |
($163.50) |
($35.46) |
$92.58 |
$220.62 |
$348.66 |
$476.70 |
$604.74 |
4. Return Metrics & Sensitivity Summary
Transaction Structuring & Partnership Terms
-
Financing Target: $13.5M technical exploration financing.
-
Entity Structure: Project-level special purpose vehicle (SPV) / asset-level partnership covering the Texas perimeter.
-
Cap Table Split:
-
80% Project Equity: Allocated to the incoming investor syndicate against $13.5M cash commitments.
-
20% Sponsor Equity: Held by the management founding entity in consideration of in-kind technical IP, proprietary geological algorithms, and desktop studies.
-
Syndicate Target: Seeking a lead investor commitment of $3.5M+ to set board governance, pacing, and tranche clearance criteria, supported by participating co-investors and corporate strategics from $1.0M+.