web analytics
Contact M&A Advisor


    Established LATEM Call Center (BPO)

    Description

    L#20261175
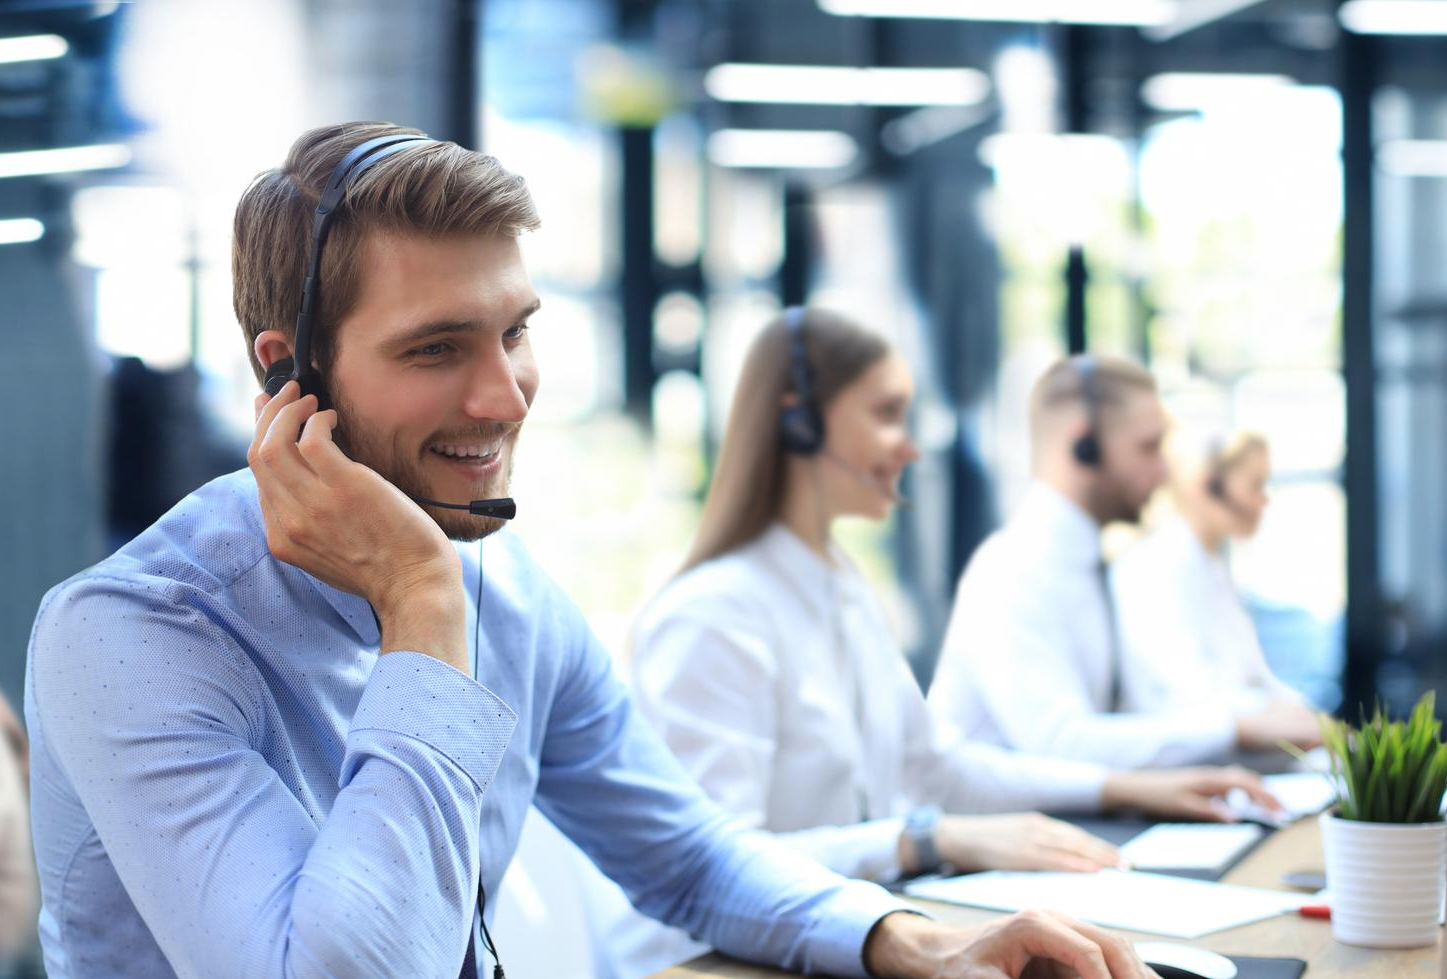
    Project Call Center represents an established Business Process Outsourcing (BPO) and omnichannel contact center platform operating across Panama (headquarters) and Colombia. 

    Platform & Infrastructure Footprint

    The company operates two production facilities with over 240 direct employees and built-in capacity to expand headcount without immediate real estate capital expenditure:
    • Panama City (Headquarters)
    • Colombia

    Client Portfolio & Commercial Concentration

    The company provides collections, customer care, sales, and technical support across four core verticals: Financial Services, Telecommunications, Retail/Utilities, and Technology.
    • Current Scale: 10 active client contracts supporting 154 contracted billable seats with 1 to 5 years of remaining contract duration.

    Financial Performance & Outlook

    Following rapid revenue growth peaking at US$3.26M in 2024, performance experienced a contraction in 2025 alongside operating margin compression.
    Metric 2021 2022 2023 2024 2025 (Mgmt. Close)
    Revenue
    US$0.37M
    US$2.19M
    US$2.96M
    US$3.26M
    US$2.49M
    EBITDA
    N/A
    -US$0.14M
    -US$0.60M
    US$0.15M
    -US$0.64M
    EBITDA Margin N/A
    -6.4%
    -20.2%
    4.6%
    -25.5%
    Historical figures reflect a mix of audited financial statements (2021), compiled reports (2024), and internal monthly management figures pending reconciliation.

    Expansion Strategy & Scaling Roadmap

    • Contracted Baseline: The core ~150-seat base remains protected via staggered contract expirations spanning 2026 through 2036.
    • 2030 Capacity Expansion: Management’s commercial pipeline aims to expand capacity to 504 total billable seats by 2030.
    • Operating Leverage: Existing physical facilities in Panama and Colombia possess surplus capacity to absorb projected seat growth without requiring near-term lease additions.

    Investment Merits vs. Key Due Diligence Areas

    Core Merits
    • Fully Licensed Turnkey Asset: Possesses rare regulatory clearances in Panama (Law 42 call center status and long-term ASEP concession).
    • Regional Arbitrage: Bi-country footprint pairs dollarized Panamanian contracting with Colombia’s cost-efficient talent pool.
    • Blue-Chip Validation: Proven delivery track record serving tier-1 regional financial and telecommunication enterprises.
    Key Due Diligence Areas
    • Client Concentration: ITS entities (Panama + Colombia) represent 68% of projected 2026 billings.
    • Turnaround Execution: Reversing the 2025 revenue decline (-23% YoY) and EBITDA margin compression (-25.5%) via operating discipline.
    • Pipeline Conversion: Validating the commercial feasibility of the 350-seat uncontracted pipeline required to reach 2030 targets.

    Basic Details

    Target Price:

    $ 3,200,000

    Gross Revenue

    $3,260,000

    EBITDA

    TBD

    Business ID:

    L#20261175

    Country

    Panama

    City:

    Panama City

    Detail

    Business ID:L#20261175
    Property Type:Call Center
    Property Status:For Sale
    Target Price: $ 3,200,000
    Gross Revenue:$ 3,260,000
    EBITDA:TBD
    Target Price / Revenue:0.98x
    Target Price / EBITDA:3200000x
    Contact M&A Advisor


      Published on September 23, 2026 at 3:35 pm. Updated on September 23, 2026 at 3:48 pm

      Project Call Center represents an established Business Process Outsourcing (BPO) and omnichannel contact center platform operating across Panama (headquarters) and Colombia. 

      Platform & Infrastructure Footprint

      The company operates two production facilities with over 240 direct employees and built-in capacity to expand headcount without immediate real estate capital expenditure:
      • Panama City (Headquarters)
      • Colombia

      Client Portfolio & Commercial Concentration

      The company provides collections, customer care, sales, and technical support across four core verticals: Financial Services, Telecommunications, Retail/Utilities, and Technology.
      • Current Scale: 10 active client contracts supporting 154 contracted billable seats with 1 to 5 years of remaining contract duration.

      Financial Performance & Outlook

      Following rapid revenue growth peaking at US$3.26M in 2024, performance experienced a contraction in 2025 alongside operating margin compression.
      Metric 2021 2022 2023 2024 2025 (Mgmt. Close)
      Revenue
      US$0.37M
      US$2.19M
      US$2.96M
      US$3.26M
      US$2.49M
      EBITDA
      N/A
      -US$0.14M
      -US$0.60M
      US$0.15M
      -US$0.64M
      EBITDA Margin N/A
      -6.4%
      -20.2%
      4.6%
      -25.5%
      Historical figures reflect a mix of audited financial statements (2021), compiled reports (2024), and internal monthly management figures pending reconciliation.

      Expansion Strategy & Scaling Roadmap

      • Contracted Baseline: The core ~150-seat base remains protected via staggered contract expirations spanning 2026 through 2036.
      • 2030 Capacity Expansion: Management’s commercial pipeline aims to expand capacity to 504 total billable seats by 2030.
      • Operating Leverage: Existing physical facilities in Panama and Colombia possess surplus capacity to absorb projected seat growth without requiring near-term lease additions.

      Investment Merits vs. Key Due Diligence Areas

      Core Merits
      • Fully Licensed Turnkey Asset: Possesses rare regulatory clearances in Panama (Law 42 call center status and long-term ASEP concession).
      • Regional Arbitrage: Bi-country footprint pairs dollarized Panamanian contracting with Colombia’s cost-efficient talent pool.
      • Blue-Chip Validation: Proven delivery track record serving tier-1 regional financial and telecommunication enterprises.
      Key Due Diligence Areas
      • Client Concentration: ITS entities (Panama + Colombia) represent 68% of projected 2026 billings.
      • Turnaround Execution: Reversing the 2025 revenue decline (-23% YoY) and EBITDA margin compression (-25.5%) via operating discipline.
      • Pipeline Conversion: Validating the commercial feasibility of the 350-seat uncontracted pipeline required to reach 2030 targets.
      MergersCorp M&A
      International As Seen On

      • brand 1
      • brand 1
      • brand 1
      • brand 1
      • brand 1