
- Home
- Logistics Company
- “Silk Road” Institutional-Grade Multi-Modal Fulfilment & Logistics Infrastructure
“Silk Road” Institutional-Grade Multi-Modal Fulfilment & Logistics Infrastructure
© 2026 MergersCorp M&A International.
© 2025 MergersCorp M&A International is a global brand operating through a number of professional firms and constituent entities (“Members”) located throughout the world to provide Investment Banking, Corporate Finance, and Advisory Services and other client-related professional services. The Member Firms (“Members”) are constituted and regulated in accordance with relevant local regulatory and legal requirements. For more details on the nature of our affiliation, please visit our Disclaimer: https://mergerscorp.com/disclaimer. MergersCorp M&A International's franchising program is not offered to individuals or entities located in the United States.
The franchising program is offered by MergersUK Limited, a UK Company with its registered office at 71-75 Shelton Street, Covent Garden, London, WC2H 9JQ, United Kingdom.
MergersCorp M&A International provides strategic business advisory services, including preparing companies for growth and capital access. Through partnerships with licensed investment bankers, clients can access tailored capital-raising solutions.
U.S. Investment Banking Securities transactions are exclusively conducted by Spektrum Capital Advisors LLC, a Registered Representative of, and Securities Products offered through, BA Securities, LLC, a FINRA-registered broker-dealer. Check the background of investment professionals associated with this site on Broker Check.
- Home
- Logistics Company
- “Silk Road” Institutional-Grade Multi-Modal Fulfilment & Logistics Infrastructure
“Silk Road” Institutional-Grade Multi-Modal Fulfilment & Logistics Infrastructure

Key Financial & Transaction Parameters
| Financial & Strategic Metric | Benchmark Value | Target Profile |
| Capital Expenditure Commitment | US$74.07M | Institutional-grade multi-modal development |
| Project Net Present Value (NPV) | US$8.24M | Risk-adjusted baseline valuation |
| Internal Rate of Return (IRR) | 20.24% | Unlevered project IRR |
| Capital Recovery Horizon | 5.2 Years | Simple payback period |
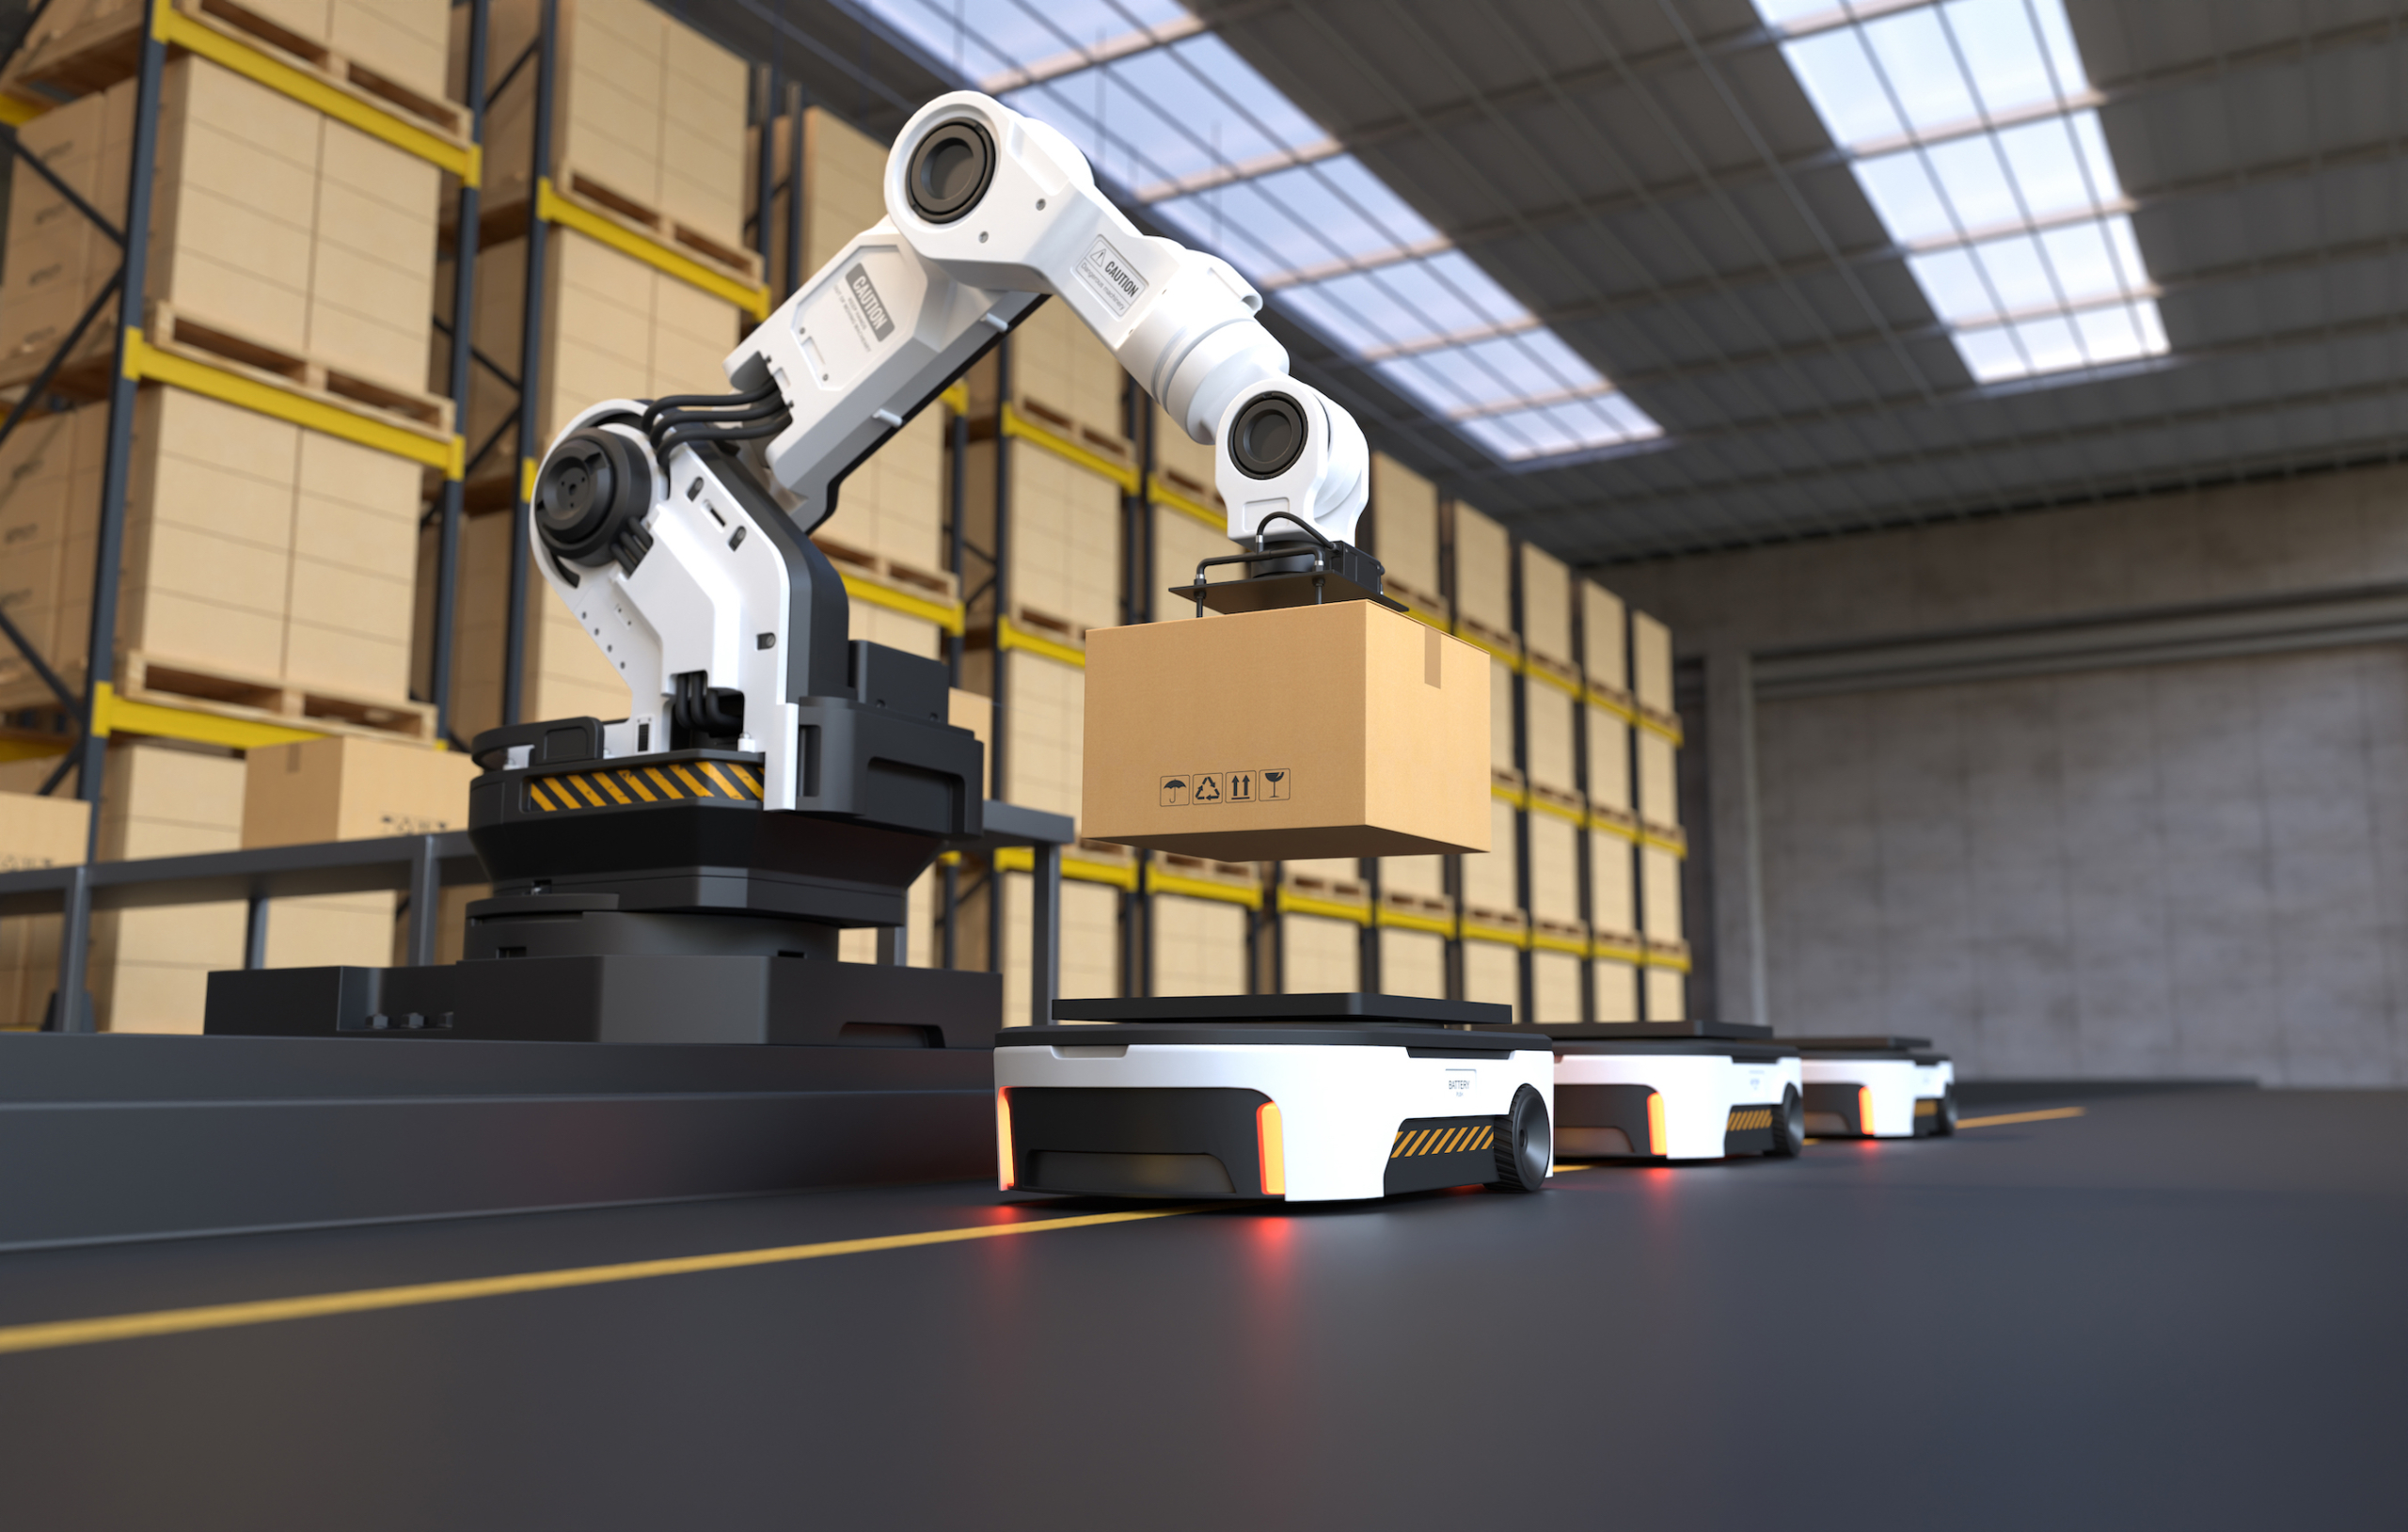
| Core Operating Model | 3PL / 4PL Hybrid | Integrated warehousing, fulfilment & bonded clearing |
| Geographic Footprint | Khorgos, Kazakhstan | Primary border gateway (direct China–EAEU transit) |
| Core Addressable Market | EAEU Cross-Border | Cross-border trade, B2B consolidation & marketplace sellers |
Core Market Dislocation & Opportunity
-
Constrained Physical Supply: Kazakhstan’s institutional warehouse footprint remains critically underdeveloped at roughly 1.4 million m², operating at a structural vacancy rate of just 0.5%.
-
Transit Velocity Arbitrage: Current parcel flows from China suffer from fragmented, point-to-point transit times averaging 3 to 6 weeks. Silk Gateway’s bonded infrastructure compresses final-mile and regional delivery down to 2 to 5 days, unlocking significant consumer adoption and inventory turn velocity.
-
Working Capital Optimization: Operating within the Khorgos SEZ framework enables Chinese exporters to deploy inventory near consumer catchments under a bonded regime, completely deferring import VAT and customs tariffs until downstream commercial settlement.
-
Under-penetrated 3PL/4PL Capacity: Freight volumes crossing Khorgos, Dostyk, and Altynkol increasingly outstrip localized value-add handling capacity, forcing reliance on basic transit rather than domestic value capture.
Value Creation & Revenue Monetization Ladder
[Basic 3PL Warehousing: US$7 / m²]
            │
            ▼
[Value-Added Fulfilment (Sorting/Pick-Pack/Multi-Temp): US$12 / m²]  (+71% Revenue Expansion)
            │
            ▼
[Integrated 4PL Solutions (Customs, Cross-Docking & Tech Integration): US$18 / m²]  (+157% Revenue Expansion)
-
Core Storage & Cross-Docking: High-turnover pallet movements and rapid freight transshipment across standard and multi-temperature footprints.
-
End-to-End E-Commerce Fulfilment: Automated sorting, piece-picking, kitting, labeling, and native marketplace integration.
-
Regulatory & Customs Intermediation: On-site bonded warehousing, regulatory compliance, and rapid clearance mechanisms.
-
4PL Orchestration: Enterprise-grade end-to-end freight visibility and distributed inventory optimization across EAEU supply chains.
Strategic Moat
-
Infrastructural Monopoly of Location: Khorgos represents the singular point of entry along the Chinese frontier integrating synchronized road, broad/standard-gauge rail transshipment, and air-adjacent corridor routing directly into the common customs territory of the EAEU.
-
Defensible Cash Flows: Long-term contractual commitments across cross-docking, temperature-controlled assets, and enterprise 4PL services provide resilient base yields paired with e-commerce volume upside.
-
First-Mover Scale Advantage: Modernizing sorting and fulfillment at the border creates a defensible network effect, locking in tier-one Chinese marketplaces seeking aggregated logistics solutions.
| Metric | Year 1 | Year 2 | Year 3 | Year 4 | Year 5 |
| Total Gross Revenue | 12.50 | 18.80 | 26.40 | 34.50 | 42.00 |
| – Basic 3PL Warehousing | 4.50 | 5.60 | 6.80 | 7.90 | 8.80 |
| – Value-Added Fulfilment | 5.00 | 8.20 | 11.50 | 14.80 | 17.50 |
| – Integrated 4PL Solutions | 3.00 | 5.00 | 8.10 | 11.80 | 15.70 |
| Cost of Goods Sold (COGS) / Direct Operating Costs | (5.63) | (8.08) | (10.82) | (13.80) | (16.38) |
| Gross Profit | 6.87 | 10.72 | 15.58 | 20.70 | 25.62 |
| Gross Margin (%) | 55.0% | 57.0% | 59.0% | 60.0% | 61.0% |
| Operating Expenses (SG&A) | (3.75) | (4.70) | (5.81) | (6.90) | (7.77) |
| – General & Administrative (G&A) | (2.25) | (2.82) | (3.49) | (4.14) | (4.66) |
| – Sales, Marketing & Technology | (1.50) | (1.88) | (2.32) | (2.76) | (3.11) |
| EBITDA | 3.12 | 6.02 | 9.77 | 13.80 | 17.85 |
| EBITDA Margin (%) | 25.0% | 32.0% | 37.0% | 40.0% | 42.5% |
Confidentiality & Transaction Governance
The information contained in this business listing is provided for informational purposes only and does not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation of any security, business, or asset by MergersCorp M&A International or its affiliates.
All financial data, operational metrics, and business details concerning the 60-year-old corrugated packaging and eco-logistics manufacturing business have been provided solely by the seller or third-party sources and have not been independently verified by MergersCorp M&A International. Prospective buyers are strongly advised to conduct their own independent due diligence, accounting, financial, legal, and regulatory audits before entering into any binding agreement or transaction.
MergersCorp M&A International makes no representations or warranties, express or implied, as to the accuracy, completeness, or reliability of the information provided herein and accepts no liability for any direct, indirect, or consequential losses resulting from reliance on this listing.
Access to detailed company documentation, financial statements, and confidential negotiations is strictly contingent upon the execution of a Non-Disclosure Agreement (NDA) and the provision of verifiable Proof of Funds (POF) + Buy Side Fee Agreement.


Description
Key Financial & Transaction Parameters
Core Market Dislocation & Opportunity
Value Creation & Revenue Monetization Ladder
Strategic Moat
Confidentiality & Transaction Governance
The information contained in this business listing is provided for informational purposes only and does not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation of any security, business, or asset by MergersCorp M&A International or its affiliates.
All financial data, operational metrics, and business details concerning the 60-year-old corrugated packaging and eco-logistics manufacturing business have been provided solely by the seller or third-party sources and have not been independently verified by MergersCorp M&A International. Prospective buyers are strongly advised to conduct their own independent due diligence, accounting, financial, legal, and regulatory audits before entering into any binding agreement or transaction.
MergersCorp M&A International makes no representations or warranties, express or implied, as to the accuracy, completeness, or reliability of the information provided herein and accepts no liability for any direct, indirect, or consequential losses resulting from reliance on this listing.
Access to detailed company documentation, financial statements, and confidential negotiations is strictly contingent upon the execution of a Non-Disclosure Agreement (NDA) and the provision of verifiable Proof of Funds (POF) + Buy Side Fee Agreement.
Basic Details
Target Price:
$ 74,000,000
Gross Revenue
$125,000,000
EBITDA
$3,120,000
Business ID:
L#20261173
Country
Kazakhstan
Detail
Published on September 23, 2026 at 8:35 am. Updated on September 23, 2026 at 8:45 am