
- Home
- Renewable Energy
- Renewable Energy - Gas & LNG
- 280MW LNG-to-Power Platform with 20-Year USD-Indexed Firm Energy Contract
280MW LNG-to-Power Platform with 20-Year USD-Indexed Firm Energy Contract
© 2026 MergersCorp M&A International.
© 2025 MergersCorp M&A International is a global brand operating through a number of professional firms and constituent entities (“Members”) located throughout the world to provide Investment Banking, Corporate Finance, and Advisory Services and other client-related professional services. The Member Firms (“Members”) are constituted and regulated in accordance with relevant local regulatory and legal requirements. For more details on the nature of our affiliation, please visit our Disclaimer: https://mergerscorp.com/disclaimer. MergersCorp M&A International's franchising program is not offered to individuals or entities located in the United States.
The franchising program is offered by MergersUK Limited, a UK Company with its registered office at 71-75 Shelton Street, Covent Garden, London, WC2H 9JQ, United Kingdom.
MergersCorp M&A International provides strategic business advisory services, including preparing companies for growth and capital access. Through partnerships with licensed investment bankers, clients can access tailored capital-raising solutions.
U.S. Investment Banking Securities transactions are exclusively conducted by Spektrum Capital Advisors LLC, a Registered Representative of, and Securities Products offered through, BA Securities, LLC, a FINRA-registered broker-dealer. Check the background of investment professionals associated with this site on Broker Check.
- Home
- Renewable Energy
- Renewable Energy - Gas & LNG
- 280MW LNG-to-Power Platform with 20-Year USD-Indexed Firm Energy Contract
280MW LNG-to-Power Platform with 20-Year USD-Indexed Firm Energy Contract

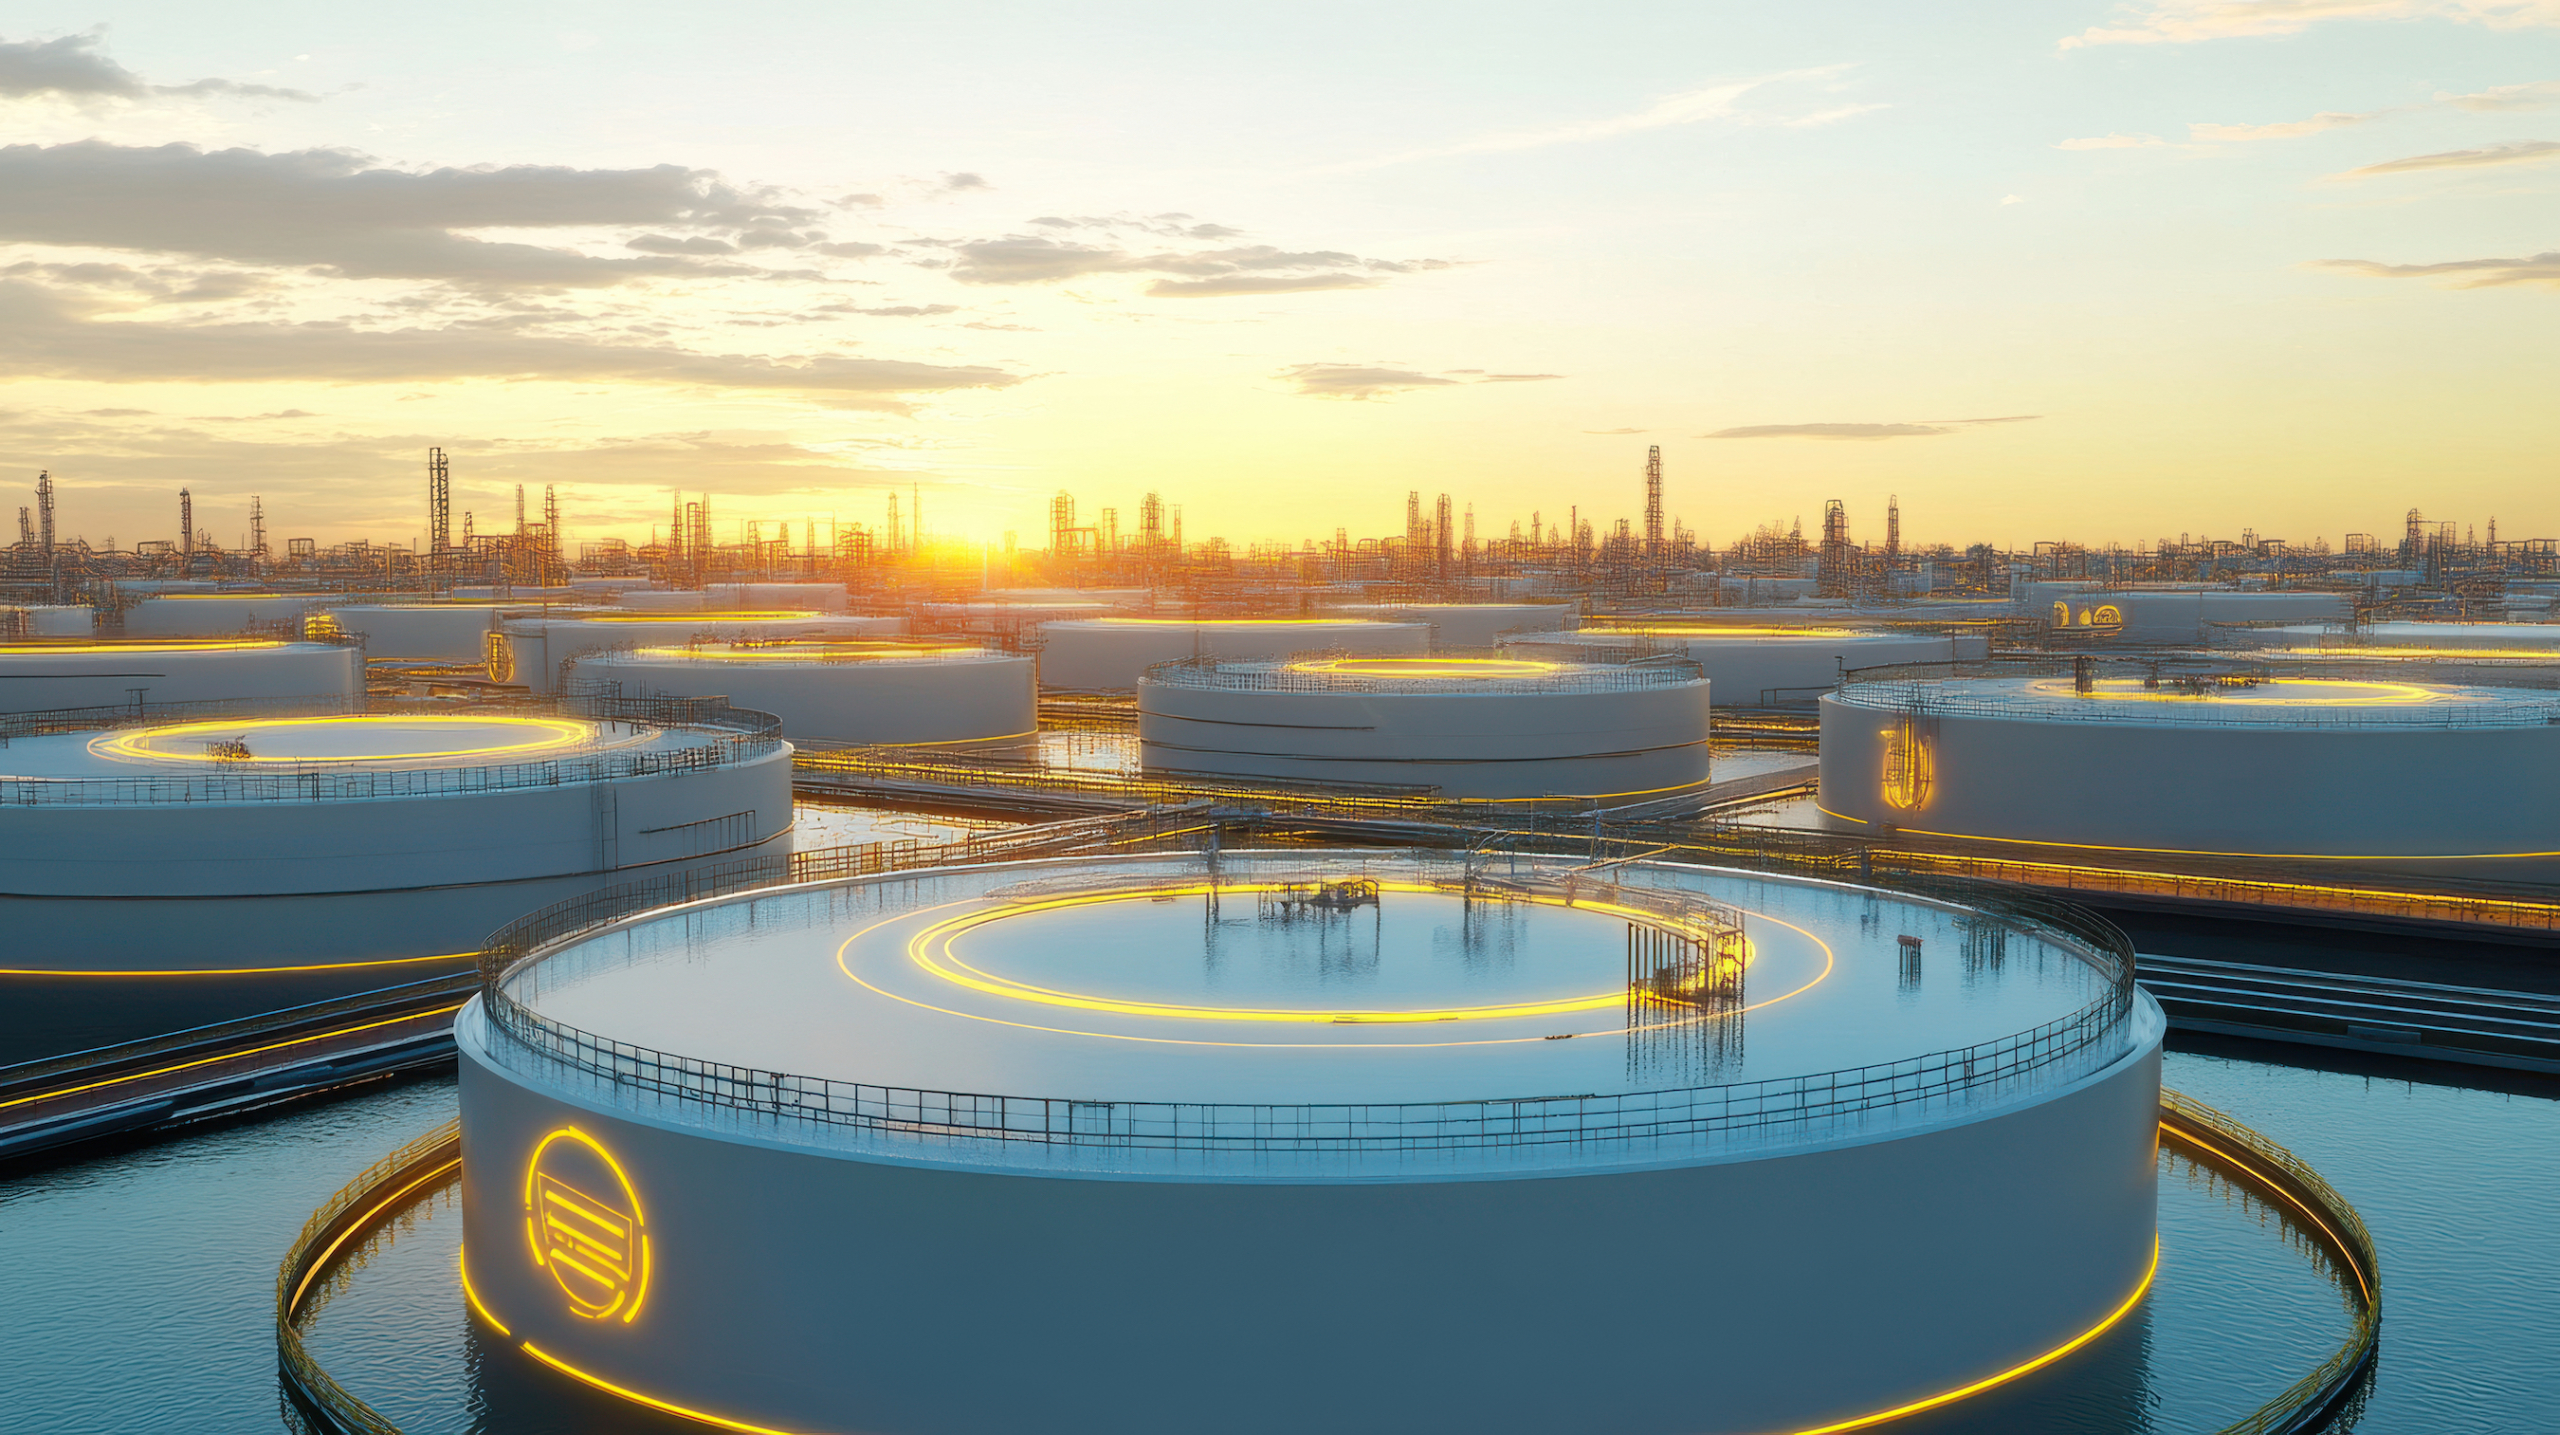
Colombia’s power system is structurally exposed: around 80% of generation is hydro, the country’s largest gas field (in production since 1977 and supplying roughly 80% of domestic output) is in decline, and El Niño droughts regularly push spot prices above USD 0.20/kWh. To secure supply, the regulator awards long-term Firm Energy Obligations (OEF) through a reliability-auction mechanism in force since 2008. USD-denominated, inflation-indexed 20-year contracts that have become one of Latin America’s most bankable power revenue streams. Against this backdrop, a privately held, family-owned energy developer offers investors participation in an integrated LNG-to-Power platform on Colombia’s Caribbean coast, anchored by a Firm Energy contract awarded in the country’s 2026 auction.
Investment Highlights
- Awarded 20-year Firm Energy contract (2029–2049): USD-denominated, indexed at PPI +2.5% p.a., no FX risk; USD 41M base annual revenue and USD 1.2B cumulative over the term
- 280 MW net dual-fuel plant (gas / ULSD): guarantees 100% dispatch during El Niño scarcity events
- Qualified expansion to 2,240 MW net (2,500 MW gross): the only LNG-to-Power project in the Colombian Firm Energy auction process
- Dedicated FSRU LNG import terminal: 170,000 m³ storage/ 400,000 MCF/day regasification; market value USD 320M at zero incremental capex to the power project
- Three linked profit streams from one asset base: contracted power revenue, FSRU gas sales margin (USD 1.18/MCF), and the terminal’s own return (target > 18% ROE)
- Advanced development stage: EPC contract (USD 195M) and engine technology selected, 220 kV interconnection <500 m from site, construction planned from 2027
- Capex-light optionality: FSRU can be owned or secured under long-term lease (USD 47–57M p.a.)
Platform Overview
The platform combines three complementary assets under one ownership group. Phase 1 is a 280 MW net (3 × 94 MW) dual-fuel reciprocating-engine plant with an awarded 20-year Firm Energy Obligation, early COD targeted for late 2027–2028 and contractual COD in 2029. Phase 2 is a qualified LNG-fuelled expansion of 2,240 MW net, interconnecting to the 500 kV national grid. Both are supplied by a dedicated floating storage and regasification unit (FSRU) located in a deep-water Caribbean port cluster with direct pipeline access to the national gas network. Beyond fuelling the plants, the terminal delivers up to 400,000 MCF/day of regasified gas to domestic utilities and industrial users, so the same infrastructure asset generates a second, independent margin. The structure supports non-recourse project financing backed by the 20-year contracted revenue stream.
Market Opportunity
Colombia’s gas market is structurally undersupplied. Domestic production is falling as the main field depletes, and the country’s only existing LNG regasification terminal serves just three power plants. Utilities, gas distributors and industrial consumers are actively seeking long-term, guaranteed supply, while the regulator continues to award Firm Energy contracts to thermal capacity able to back up the hydro-dependent grid. The platform’s site is the only viable Caribbean location combining a deep-water port, an existing generation cluster and pipeline connectivity, positioning it as the natural replacement for declining domestic supply and as a strategic asset for LNG midstream, trading and power players entering the Andean market.
Financial Snapshot
| Metric | Value | Basis |
| Contracted volume | ~6,500 MWh/day | Firm Energy Obligation, 20 years |
| Year-1 base revenue | ~USD 41.1M | PCVS USD 16–17/MWh, indexed PPI + 2.5% p.a. |
| 20-yr cumulative revenue | ~USD 1.2B | 2029–2049, USD-denominated |
| Phase 1 EPC value | ~USD 195M | Consolidated EPC contract |
| FSRU market value | ~USD 320M | Zero incremental capex to power project |
| LNG terminal capital cost | < USD 325M | Or long-term lease at USD 47–57M p.a. |
| Gas sales margin | ~USD 1.18 / MCF | On up to 400,000 MCF/day |
| Target return | > 18% ROE | LNG import project |
| Key milestones | 2027–2028 / mid-2028 | Phase 1 construction & early COD/ terminal commissioning |
| Line Item (USD M) | Year 1 (2029) | Year 5 (2033) | Year 10 (2038) | Year 15 (2043) | Year 20 (2048) |
| Firm Energy Revenue (OEF) | $41.1 | $49.0 | $61.1 | $76.1 | $94.8 |
| Power Plant Fixed O&M | ($8.5) | ($9.4) | ($10.6) | ($12.0) | ($13.6) |
| Insurance, SG&A, Land Leases | ($3.0) | ($3.3) | ($3.7) | ($4.2) | ($4.8) |
| EBITDA | $29.6 | $36.3 | $46.8 | $59.9 | $76.4 |
| EBITDA Margin | 72.0% | 74.1% | 76.6% | 78.7% | 80.6% |
| Depreciation (20-yr Straight-Line) | ($11.0) | ($11.0) | ($11.0) | ($11.0) | ($11.0) |
| EBIT | $18.6 | $25.3 | $35.8 | $48.9 | $65.4 |
| Senior Interest Expense | ($11.6) | ($9.5) | ($5.9) | ($0.9) | $0.0 |
| EBT | $7.0 | $15.8 | $29.9 | $48.0 | $65.4 |
| Corporate Income Tax (35%) | ($2.5) | ($5.5) | ($10.5) | ($16.8) | ($22.9) |
| Net Income | $4.5 | $10.3 | $19.4 | $31.2 | $42.5 |
| (+) Depreciation & Non-Cash | $11.0 | $11.0 | $11.0 | $11.0 | $11.0 |
| (-) Senior Debt Principal Amortization | ($5.8) | ($7.8) | ($11.3) | ($16.4) | $0.0 |
| Free Cash Flow to Equity (FCFE) | $9.7 | $13.5 | $19.1 | $25.8 | $53.5 |
| Debt Service Coverage Ratio (DSCR) | 1.70x | 2.10x | 2.72x | 3.46x | N/A (Debt Free) |


Description
Colombia’s power system is structurally exposed: around 80% of generation is hydro, the country’s largest gas field (in production since 1977 and supplying roughly 80% of domestic output) is in decline, and El Niño droughts regularly push spot prices above USD 0.20/kWh. To secure supply, the regulator awards long-term Firm Energy Obligations (OEF) through a reliability-auction mechanism in force since 2008. USD-denominated, inflation-indexed 20-year contracts that have become one of Latin America’s most bankable power revenue streams. Against this backdrop, a privately held, family-owned energy developer offers investors participation in an integrated LNG-to-Power platform on Colombia’s Caribbean coast, anchored by a Firm Energy contract awarded in the country’s 2026 auction.
Investment Highlights
Platform Overview
The platform combines three complementary assets under one ownership group. Phase 1 is a 280 MW net (3 × 94 MW) dual-fuel reciprocating-engine plant with an awarded 20-year Firm Energy Obligation, early COD targeted for late 2027–2028 and contractual COD in 2029. Phase 2 is a qualified LNG-fuelled expansion of 2,240 MW net, interconnecting to the 500 kV national grid. Both are supplied by a dedicated floating storage and regasification unit (FSRU) located in a deep-water Caribbean port cluster with direct pipeline access to the national gas network. Beyond fuelling the plants, the terminal delivers up to 400,000 MCF/day of regasified gas to domestic utilities and industrial users, so the same infrastructure asset generates a second, independent margin. The structure supports non-recourse project financing backed by the 20-year contracted revenue stream.
Market Opportunity
Colombia’s gas market is structurally undersupplied. Domestic production is falling as the main field depletes, and the country’s only existing LNG regasification terminal serves just three power plants. Utilities, gas distributors and industrial consumers are actively seeking long-term, guaranteed supply, while the regulator continues to award Firm Energy contracts to thermal capacity able to back up the hydro-dependent grid. The platform’s site is the only viable Caribbean location combining a deep-water port, an existing generation cluster and pipeline connectivity, positioning it as the natural replacement for declining domestic supply and as a strategic asset for LNG midstream, trading and power players entering the Andean market.
Financial Snapshot
Basic Details
Target Price:
$ 0
Gross Revenue
$41,110,000
EBITDA
$29,600,000
Business ID:
L#20261158
Country
Colombia
Detail
Published on September 15, 2026 at 9:24 am. Updated on September 15, 2026 at 9:24 am