web analytics
Contact M&A Advisor


    199 MW Italian Battery Energy Storage System BESS

    Description

    L#20261171

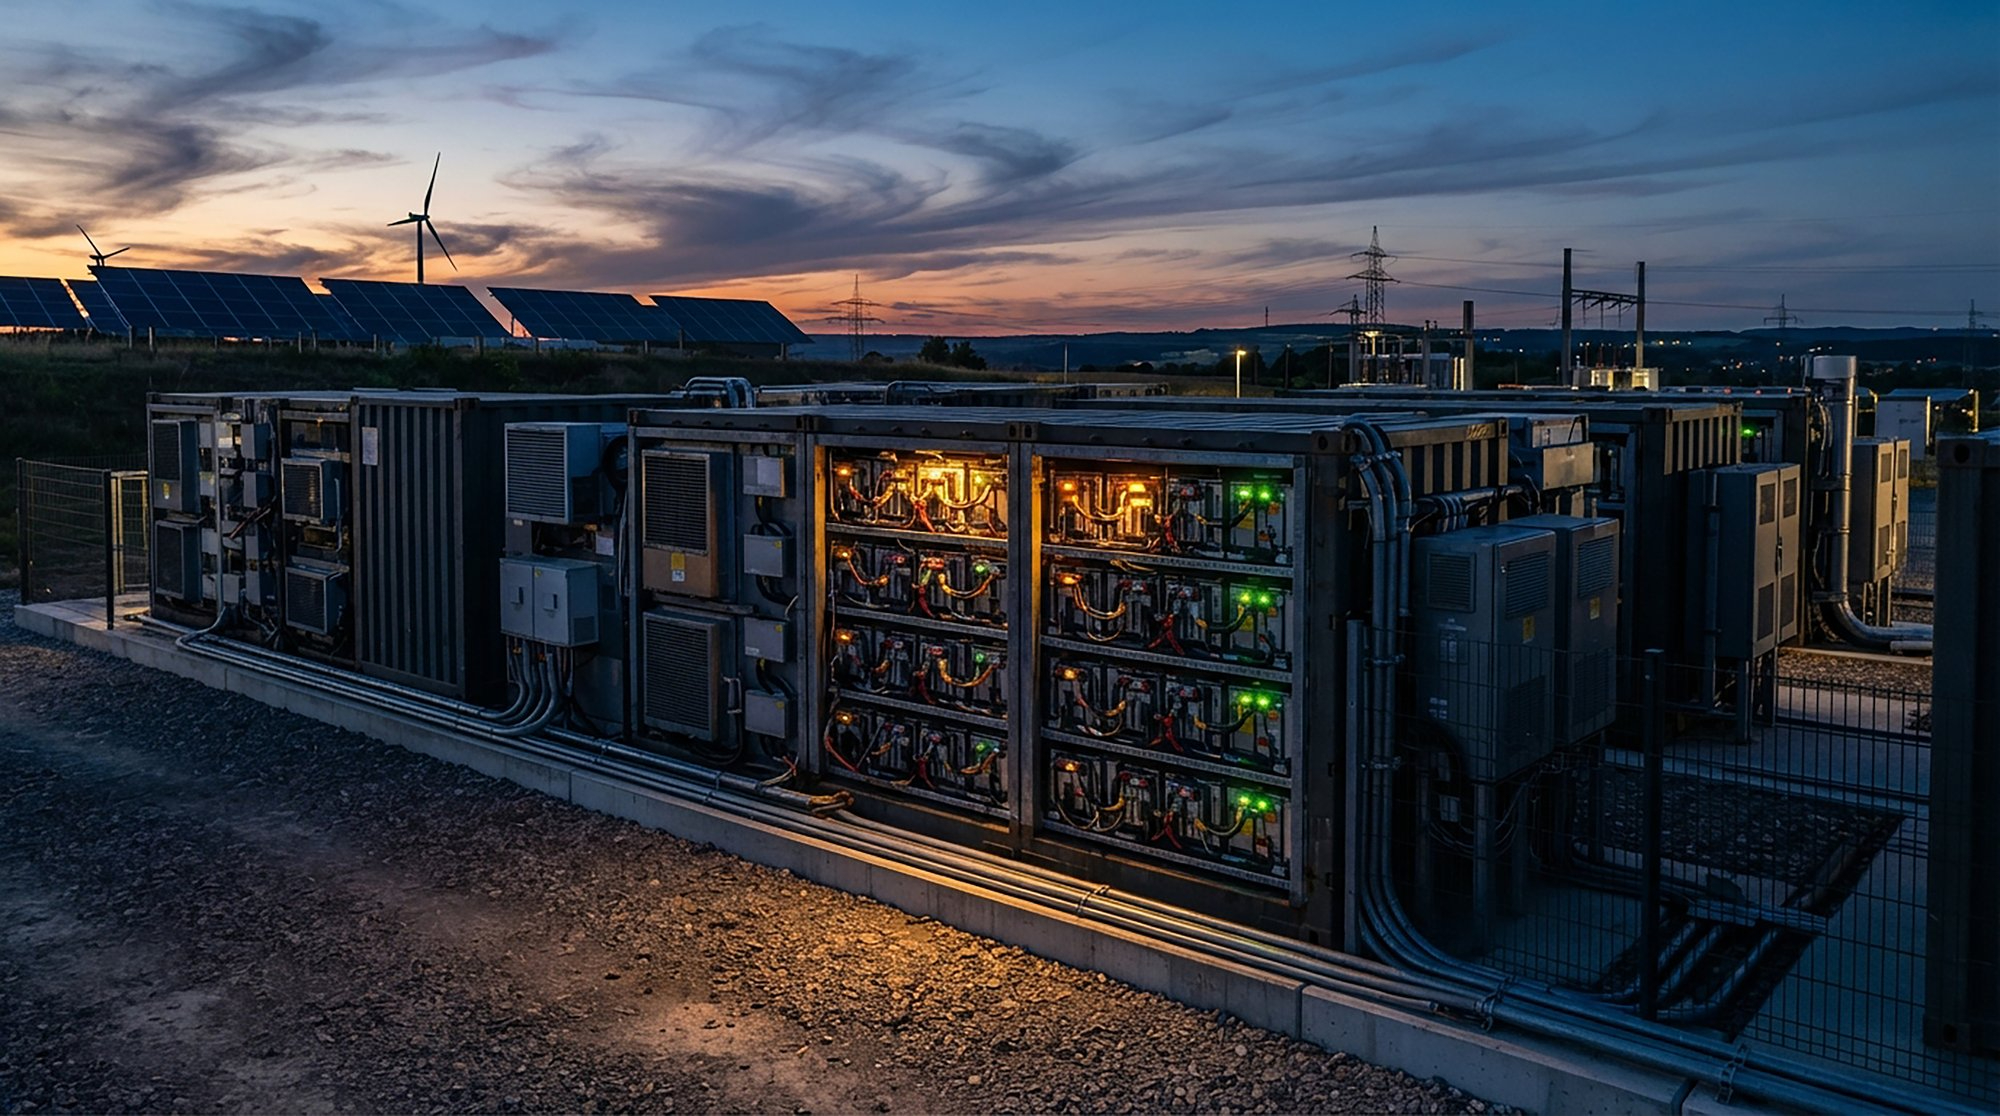
    A utility-scale Battery Energy Storage System (BESS) development opportunity located in Oristano, Sardinia). The project targets a nominal power capacity of 199 MW on a 7.5-hectare plot situated merely 0.1 km from an existing 220 kV Terna electrical substation. The proposal outlines an acquisition pathway to Ready-to-Build (RTB) status via a 100% SPV share transfer, supported by an accepted grid connection (PTO) and an ongoing Single Authorization (Autorizzazione Unica – AU) permitting process with an estimated 18-month lead time.

    Project Overview

    • Total Land Area: 7.5 hectares (ha)
    • Net Usable Area: ~4.9 ha (2.6 ha restricted under high hydraulic hazard Hi4; unusable for BESS containers but compatible for auxiliary layout)
    • Grid Connection: Existing 220 kV Terna Electrical Substation (SSE Fenosu) located approximately 0.1 km away
    • Grid Status: Connection accepted and PTO confirmed; connection fees paid
    • Permitting Status: Single Authorization (Autorizzazione Unica – AU) submission phase
    • Estimated Permitting Timeline: 18 months to achieve Ready-to-Build (RTB) status

    Transaction Structure & Acquisition Terms

    The transaction is structured as a staged development agreement leading to 100% SPV equity acquisition at the Ready-to-Build (RTB) milestone:
    Initial Deposit (Milestone 1): 15% upfront deposit of the total developer fee upon contract signing (€6,750/MW), conferring a commitment on the SPV shares
    • Reimbursements: Buyer reimburses developer costs incurred for the land deposit and the acceptance of the STMG.
    • AU Support & Guarantees: Buyer must provide financial guarantees verifying fund availability for plant construction as required for AU issuance.
    • Final Closing Payment (Milestone 2 – RTB): Acquisition of 100% SPV equity upon AU issuance for the remaining 85% developer fee (€38,250/MW).
    • Excluded Buyer Obligations: Buyer directly covers the remaining purchase cost of the land and the balance of STMG grid connection charges.

    Financial Model (Acquisition & Development CapEx Breakdown)

    Item Unit Rate Basis / Formula Total Commitment (€) Notes
    Developer Success Fee – Deposit (15%) €6,750 / MW
    199 MW × 15%
    €1,343,250
    Payable upon signing contract
    Developer Success Fee – RTB (85%) €38,250 / MW
    199 MW × 85%
    €7,611,750
    Payable at AU approval (turnkey transfer)
    Total SPV Acquisition Consideration €45,000 / MW 199 MW €8,955,000 Total M&A Developer Fee
    Land Purchase Consideration
    €100,000 / ha
    7.5 ha
    €750,000
    Net of initial developer deposit reimbursement
    STMG Connection Fee Reimbursement & Final Balance At cost
    Pass-through
    To be finalized
    Initial STMG acceptance paid; balance due per Terna STMG
    Land Deposit Reimbursement At cost
    Pass-through
    To be finalized
    Developer advance payment to be reimbursed
    Total Pre-Construction Capital Outlay (Base) SPV Equity + Land €9,705,000 Excluding STMG balance and financing fees

    4. Key Constraints & Technical Feasibility

    • Hydraulic Hazard (PAI): A 2.6 ha section is classified as Hi4 (high hydraulic risk). The remaining 4.9 ha provides sufficient footprint for the 199 MW containerized BESS installation.
    • High-Voltage Easements: The parcel is traversed by three high-voltage lines due to its immediate adjacency (100 m) to the Terna substation. Ground reservations directly below conductors will serve as access roads, underground routing corridors, and maneuvering areas pursuant to Fire Brigade (VVF) guidelines.
    • Hydraulic Buffers: The Spinarba reclamation canal crosses the land; its regulated buffer falls entirely within the pre-existing Hi4 footprint and creates no incremental restriction.
    Line Item Year 1 Year 2 Year 3 Year 4 Year 5 Notes / Drivers
    Installed Capacity (MW)
    199
    199
    199
    199
    199
    Full commercial operation
    Capacity / Availability Revenue €9.950 €9.950 €9.950 €9.950 €9.950 €50k/MW contracted floor / MACSE-CM
    Arbitrage & Balancing Revenue (MSD/MGP) €6.965 €6.825 €6.690 €6.555 €6.425 Net spreads after cycle efficiency & degradation
    Total Gross Revenues €16.915 €16.775 €16.640 €16.505 €16.375 Base average ~€85k/MW/year
    Fixed & Scheduled O&M (€1.393) (€1.421) (€1.449) (€1.478) (€1.508) Long-Term Service Agreement (LTSA)
    Insurance & Asset Management (€696) (€710) (€724) (€739) (€754) Property, liability, SPV compliance
    Battery Augmentation & Balance of Plant (€1.194) (€1.218) (€1.242) (€1.267) (€1.292) Reserve provisioning for degradation
    Total Operating Expenses (OpEx) (€3.283) (€3.349) (€3.415) (€3.484) (€3.554) Escalated at 2.0% per annum
    Project EBITDA €13.632 €13.426 €13.225 €13.021 €12.821 Steady-state operating cash generation
    EBITDA Margin (%) 80,6% 80,0% 79,5% 78,9% 78,3% Typical profile for utility-scale BESS

    Disclaimer and Legal Notice

    Confidentiality & Non-Disclosure
    This document, along with any accompanying presentations, financial analyses, appendices, or communications (collectively, the “Information”), is confidential and has been prepared strictly for information and evaluation purposes. The Information is intended solely for the recipient and may not be copied, reproduced, distributed, summarized, or passed on to any other person, in whole or in part, without prior written consent. By accepting this material, the recipient agrees to keep all matters contained herein confidential.
    No Offer or Commitment
    The Information does not constitute, nor shall it be construed as, an offer to sell, a solicitation of an offer to purchase, or a recommendation to acquire any securities, shares in special purpose vehicles (SPVs), project assets, or financial instruments. Nothing contained herein shall form the basis of, or be relied on in connection with, any contract, binding transaction, or investment commitment. Any binding agreement shall be governed solely by definitive transaction documentation negotiated, agreed, and executed between the relevant parties.
    Nature of Financial Projections & Forward-Looking Statements
    All pro-forma figures, operational benchmarks, estimates, market revenue forecasts (including capacity remuneration, arbitrage, and ancillary services), operating expense reserves, and internal rate of return (IRR) projections contained herein represent forward-looking statements. These projections are indicative only and are based on subjective assumptions, technical estimates, prevailing regulatory environments, and market market conditions that are inherently uncertain. Actual results, operational performance, and financial returns may differ materially from those expressed or implied due to numerous factors, including but not limited to:
    • Fluctuations in electricity market pricing, day-ahead spreads, and ancillary services remuneration;
    • Changes in national or European energy policies, procurement auctions (e.g., MACSE, Capacity Market), and grid tariff regulations;
    • Permitting delays, environmental conditions, or modifications imposed during the Single Authorization (Autorizzazione Unica – AU) procedure;
    • Variations in construction costs, supply chain delivery schedules, battery cell pricing, and interest/debt financing rates;
    • Physical operational factors such as equipment degradation, grid curtailment, or interconnection modifications by the transmission system operator (Terna).
    No Representations or Warranties / Independent Due Diligence
    No representation, warranty, or undertaking, express or implied, is made by the developer, its advisors, affiliates, directors, or representatives regarding the accuracy, completeness, or reasonableness of the Information. The recipient must conduct its own independent technical, environmental, legal, financial, and tax due diligence. The recipient is advised to consult its own legal, regulatory, and financial advisors prior to entering into any agreement or incurring any financial obligations.

    Basic Details

    Target Price:

    EUR 8,955,000

    Gross Revenue

    €16,915,000

    EBITDA

    €16,632,000

    Business ID:

    L#20261171

    Country

    Italy

    City:

    Oristano

    Detail

    Business ID:L#20261171
    Property Type:Renewable Energy - Solar PV & BESS
    Property Status:For Sale
    Target Price: EUR 8,955,000
    Gross Revenue:EUR 16,915,000
    EBITDA:EUR 16,632,000
    Target Price / Revenue:0.53x
    Target Price / EBITDA:0.54x
    Contact M&A Advisor


      Published on September 20, 2026 at 7:49 pm. Updated on September 20, 2026 at 8:01 pm

      A utility-scale Battery Energy Storage System (BESS) development opportunity located in Oristano, Sardinia). The project targets a nominal power capacity of 199 MW on a 7.5-hectare plot situated merely 0.1 km from an existing 220 kV Terna electrical substation. The proposal outlines an acquisition pathway to Ready-to-Build (RTB) status via a 100% SPV share transfer, supported by an accepted grid connection (PTO) and an ongoing Single Authorization (Autorizzazione Unica – AU) permitting process with an estimated 18-month lead time.

      Project Overview

      • Total Land Area: 7.5 hectares (ha)
      • Net Usable Area: ~4.9 ha (2.6 ha restricted under high hydraulic hazard Hi4; unusable for BESS containers but compatible for auxiliary layout)
      • Grid Connection: Existing 220 kV Terna Electrical Substation (SSE Fenosu) located approximately 0.1 km away
      • Grid Status: Connection accepted and PTO confirmed; connection fees paid
      • Permitting Status: Single Authorization (Autorizzazione Unica – AU) submission phase
      • Estimated Permitting Timeline: 18 months to achieve Ready-to-Build (RTB) status

      Transaction Structure & Acquisition Terms

      The transaction is structured as a staged development agreement leading to 100% SPV equity acquisition at the Ready-to-Build (RTB) milestone:
      Initial Deposit (Milestone 1): 15% upfront deposit of the total developer fee upon contract signing (€6,750/MW), conferring a commitment on the SPV shares
      • Reimbursements: Buyer reimburses developer costs incurred for the land deposit and the acceptance of the STMG.
      • AU Support & Guarantees: Buyer must provide financial guarantees verifying fund availability for plant construction as required for AU issuance.
      • Final Closing Payment (Milestone 2 – RTB): Acquisition of 100% SPV equity upon AU issuance for the remaining 85% developer fee (€38,250/MW).
      • Excluded Buyer Obligations: Buyer directly covers the remaining purchase cost of the land and the balance of STMG grid connection charges.

      Financial Model (Acquisition & Development CapEx Breakdown)

      Item Unit Rate Basis / Formula Total Commitment (€) Notes
      Developer Success Fee – Deposit (15%) €6,750 / MW
      199 MW × 15%
      €1,343,250
      Payable upon signing contract
      Developer Success Fee – RTB (85%) €38,250 / MW
      199 MW × 85%
      €7,611,750
      Payable at AU approval (turnkey transfer)
      Total SPV Acquisition Consideration €45,000 / MW 199 MW €8,955,000 Total M&A Developer Fee
      Land Purchase Consideration
      €100,000 / ha
      7.5 ha
      €750,000
      Net of initial developer deposit reimbursement
      STMG Connection Fee Reimbursement & Final Balance At cost
      Pass-through
      To be finalized
      Initial STMG acceptance paid; balance due per Terna STMG
      Land Deposit Reimbursement At cost
      Pass-through
      To be finalized
      Developer advance payment to be reimbursed
      Total Pre-Construction Capital Outlay (Base) SPV Equity + Land €9,705,000 Excluding STMG balance and financing fees

      4. Key Constraints & Technical Feasibility

      • Hydraulic Hazard (PAI): A 2.6 ha section is classified as Hi4 (high hydraulic risk). The remaining 4.9 ha provides sufficient footprint for the 199 MW containerized BESS installation.
      • High-Voltage Easements: The parcel is traversed by three high-voltage lines due to its immediate adjacency (100 m) to the Terna substation. Ground reservations directly below conductors will serve as access roads, underground routing corridors, and maneuvering areas pursuant to Fire Brigade (VVF) guidelines.
      • Hydraulic Buffers: The Spinarba reclamation canal crosses the land; its regulated buffer falls entirely within the pre-existing Hi4 footprint and creates no incremental restriction.
      Line Item Year 1 Year 2 Year 3 Year 4 Year 5 Notes / Drivers
      Installed Capacity (MW)
      199
      199
      199
      199
      199
      Full commercial operation
      Capacity / Availability Revenue €9.950 €9.950 €9.950 €9.950 €9.950 €50k/MW contracted floor / MACSE-CM
      Arbitrage & Balancing Revenue (MSD/MGP) €6.965 €6.825 €6.690 €6.555 €6.425 Net spreads after cycle efficiency & degradation
      Total Gross Revenues €16.915 €16.775 €16.640 €16.505 €16.375 Base average ~€85k/MW/year
      Fixed & Scheduled O&M (€1.393) (€1.421) (€1.449) (€1.478) (€1.508) Long-Term Service Agreement (LTSA)
      Insurance & Asset Management (€696) (€710) (€724) (€739) (€754) Property, liability, SPV compliance
      Battery Augmentation & Balance of Plant (€1.194) (€1.218) (€1.242) (€1.267) (€1.292) Reserve provisioning for degradation
      Total Operating Expenses (OpEx) (€3.283) (€3.349) (€3.415) (€3.484) (€3.554) Escalated at 2.0% per annum
      Project EBITDA €13.632 €13.426 €13.225 €13.021 €12.821 Steady-state operating cash generation
      EBITDA Margin (%) 80,6% 80,0% 79,5% 78,9% 78,3% Typical profile for utility-scale BESS

      Disclaimer and Legal Notice

      Confidentiality & Non-Disclosure
      This document, along with any accompanying presentations, financial analyses, appendices, or communications (collectively, the “Information”), is confidential and has been prepared strictly for information and evaluation purposes. The Information is intended solely for the recipient and may not be copied, reproduced, distributed, summarized, or passed on to any other person, in whole or in part, without prior written consent. By accepting this material, the recipient agrees to keep all matters contained herein confidential.
      No Offer or Commitment
      The Information does not constitute, nor shall it be construed as, an offer to sell, a solicitation of an offer to purchase, or a recommendation to acquire any securities, shares in special purpose vehicles (SPVs), project assets, or financial instruments. Nothing contained herein shall form the basis of, or be relied on in connection with, any contract, binding transaction, or investment commitment. Any binding agreement shall be governed solely by definitive transaction documentation negotiated, agreed, and executed between the relevant parties.
      Nature of Financial Projections & Forward-Looking Statements
      All pro-forma figures, operational benchmarks, estimates, market revenue forecasts (including capacity remuneration, arbitrage, and ancillary services), operating expense reserves, and internal rate of return (IRR) projections contained herein represent forward-looking statements. These projections are indicative only and are based on subjective assumptions, technical estimates, prevailing regulatory environments, and market market conditions that are inherently uncertain. Actual results, operational performance, and financial returns may differ materially from those expressed or implied due to numerous factors, including but not limited to:
      • Fluctuations in electricity market pricing, day-ahead spreads, and ancillary services remuneration;
      • Changes in national or European energy policies, procurement auctions (e.g., MACSE, Capacity Market), and grid tariff regulations;
      • Permitting delays, environmental conditions, or modifications imposed during the Single Authorization (Autorizzazione Unica – AU) procedure;
      • Variations in construction costs, supply chain delivery schedules, battery cell pricing, and interest/debt financing rates;
      • Physical operational factors such as equipment degradation, grid curtailment, or interconnection modifications by the transmission system operator (Terna).
      No Representations or Warranties / Independent Due Diligence
      No representation, warranty, or undertaking, express or implied, is made by the developer, its advisors, affiliates, directors, or representatives regarding the accuracy, completeness, or reasonableness of the Information. The recipient must conduct its own independent technical, environmental, legal, financial, and tax due diligence. The recipient is advised to consult its own legal, regulatory, and financial advisors prior to entering into any agreement or incurring any financial obligations.

      MergersCorp M&A
      International As Seen On

      • brand 1
      • brand 1
      • brand 1
      • brand 1
      • brand 1